Minnesota United at Orlando City: Keys to the match, projected starting XI and a prediction

posted in: News | 0

Minnesota United at Orlando City

When: 6:30 p.m. CT Saturday

Where: Inter&Co Stadium, Orlando, Fla.

Stream: Apple TV Season Pass

Radio: KSTP-AM 1500 ESPN

Weather: 83 degrees, partly cloudy, 14 mph north wind

Betting line: Orlando minus-115; draw plus-280; MNUFC plus-265

Series history: MNUFC is 2-1-1 against Orlando City in MLS. Loons suffered their first loss, 2-1, to the Lions at Allianz Field last April.

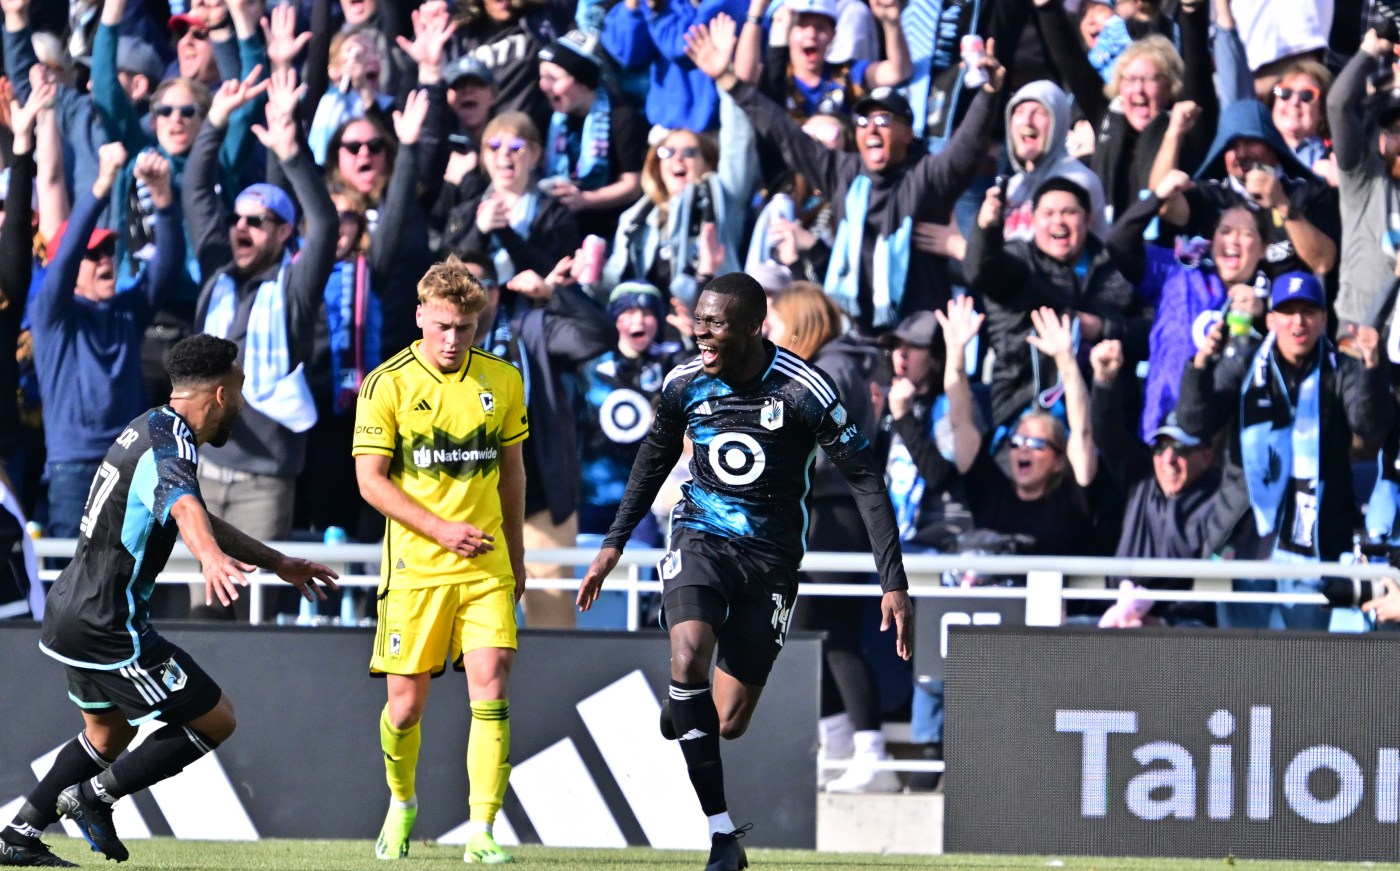
Synopsis: Interim head coach Cameron Knowles will lead the Loons first team for the last time before permanent head coach Eric Ramsay arrives this weekend. Knowles has impressed with the players’ buy-in to new high pressing style and earn points despite a shorthanded roster.

Form: Minnesota United (1-0-1) have four points through two games, but weren’t as strong in a 1-1 draw with MLS Cup Champion Columbus Crew last Saturday. Orlando City (0-1-1) advanced to Eastern Conference semifinal last year, but are scoreless through two MLS games. They had a scoreless draw with Montreal and were demolished 5-0 by Lionel Messi and Inter Miami last weekend. Orlando played to a scoreless home draw with Mexican giant Tigres in the Concacaf Champions Cup last Tuesday and must go to Monterrey for a difficult second leg on Tuesday.

Quote: “It’s challenging,” Wil Trapp said of Orlando’s schedule. “There are more games. There is more travel. There is rotation in squad. And it all comes pretty quick, so I don’t read too much into maybe some of the league form.”

Projected XI: In a 4-3-3 formation, LW Caden Clark, CF Teemu Pukki, RW Sang Bin Jeong; CM Hassani Dotson, CM Kervin Arriaga, CM Wil Trapp; LB Joseph Rosales, CB Micky Tapias, CB Michael Boxall, RB DJ Taylor; GK Dayne St. Clair.

Absences: Bongi Hlongwane (fitness) and Robin Lod are available to play, but seem more likely to come off the bench. Emanuel Reynoso (knee) and Franco Fragapane (calf) remain out. Loons are hopeful Reynoso can make his season debut against LAFC next Saturday. Orlando attacker Facundo Torres, who led Lions with 14 goals last season, fell hard on his shoulder and exited the Tigres tie in the 60th minute. MLS availability reports have not yet been issued.

Opinion: Restrictive rules from MLS hurt a club’s ability to make call-ups from second teams, while stifling players’ development. Look no further than Lakeville South graduate Loic Mesanvi. The 20-year-old winger had only two chances to be called up for MLS games this season, and those opportunities are exhausted after the opening two matches.

Scouting point: Orlando forward Duncan McGuire had 13 goals as a rookie last season and the 21-year-old Nebraska native’s movement has impressed Knowles since McGuire played for Creighton. “He is a real handful,” Knowles said. “His ability to score … and his ability to look to run in behind and stretch the game.”

Key player: South Korean winger Jeong, who MLS clocked as the fastest player (22.5 mph) in the league in the opening week, flashed again versus the Crew. He had a handful of successful dribbles (including nutmegs), four shot-creating actions and 0.5 expected assists.

Prediction: MLS clubs juggling Concacaf Champions Cup and MLS play often start slow in league games. Orlando is yet another example. This combination serves as the Loons’ chance to get a result against a top preseason pick in the East. After nearly connecting for a goal against Columbus, Jeong dishes for a Pukki finish in a 1-1 draw.

With time winding down on trade deadline, Wild complete two minor deals

posted in: News | 0

DENVER — On deadline day, there were no fireworks from Bill Guerin, which is pretty much what the Wild general manager previewed before Friday’s 2 p.m. CT last call.

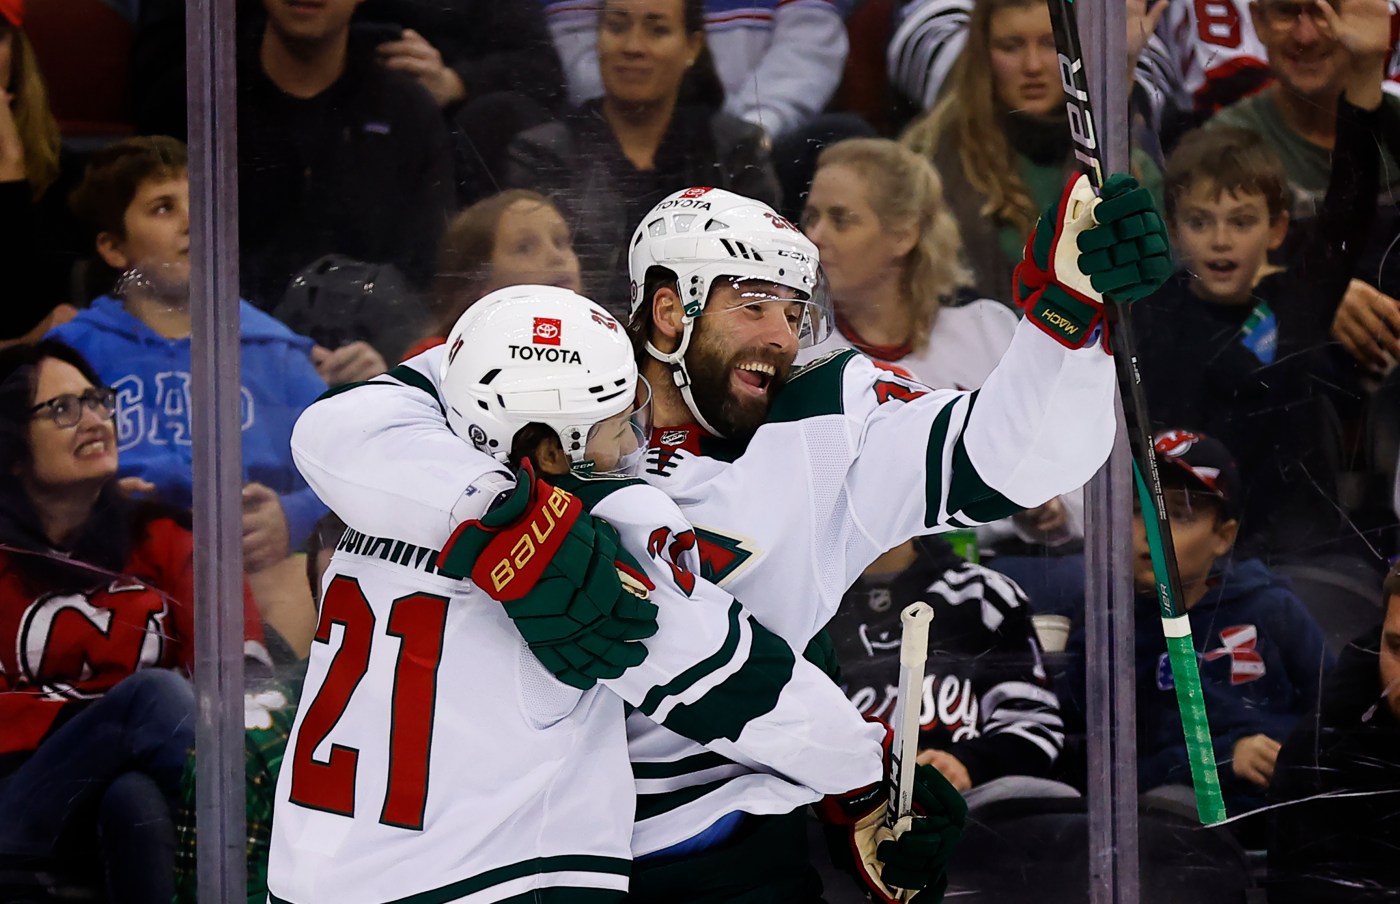
Guerin sent injured forward Pat Maroon to Boston for prospect Luke Toporowski and a conditional sixth-round pick in the 2026 entry draft, and swapped Iowa center Nick Petan to the New York Rangers for veteran forward Turner Elson.

Both acquisitions will report to the Wild’s American Hockey League team in Des Moines.

Toporowski, 22, had 22 goals and 46 points in 96 games with the Providence Bruins. Maroon, 35, is on injured reserve after undergoing back surgery last month. He began skating on his own this week.

Meanwhile, Brandon Duhaime, traded Thursday to Colorado, was at Ball Arena preparing to meet his former team at 8 p.m. Wednesday. The forward said he expected to be in the lineup. A pending unrestricted free agent, Duhaime packed extra clothes for the Wild’s two-game road trip because he suspected he might be traded before Friday.

“I was pretty aware of the situation, but it’s part of the business, part of the game, and I’m happy to be here,” he said. “Excited to be here.”

The Wild started the day seven points out of the eighth and final playoff spot in the Western Conference, while the Avalanche were fourth, by percentage points behind Winnipeg, and six points behind first-place Vancouver. His initial reaction to the trade, Duhaime said, was, “excitement, for sure.”

“Being part of a team like this and how good they are and their momentum and where they’re headed right now, it’s a good path,” he said Friday after a morning skate with his new team. “And I’m excited to be on this journey with them.”

Briefly

Kirill Kaprizov’s second-period power-play goal in Thursday’s 5-2 victory at Arizona gave him 30 goals for 2023-24, and made him the first Wild player to score at least 30 in three consecutive seasons.

Related Articles

Minnesota Wild |


Wild remain Marc-Andre Fleury’s playoff contender

Minnesota Wild |


Shorthanded Wild have enough to beat Coyotes

Minnesota Wild |


Brandon Duhaime trade on the players, Wild veteran Marcus Foligno says

Minnesota Wild |


Wild, Zach Bogosian agree to two-year, $2.5 million extension

Minnesota Wild |


John Shipley: Wild have few trade options, but maybe Bill Guerin will surprise us

Chicago Bears hire Eric Washington — ‘a great communicator with elite leadership skills’ — as defensive coordinator

posted in: News | 0

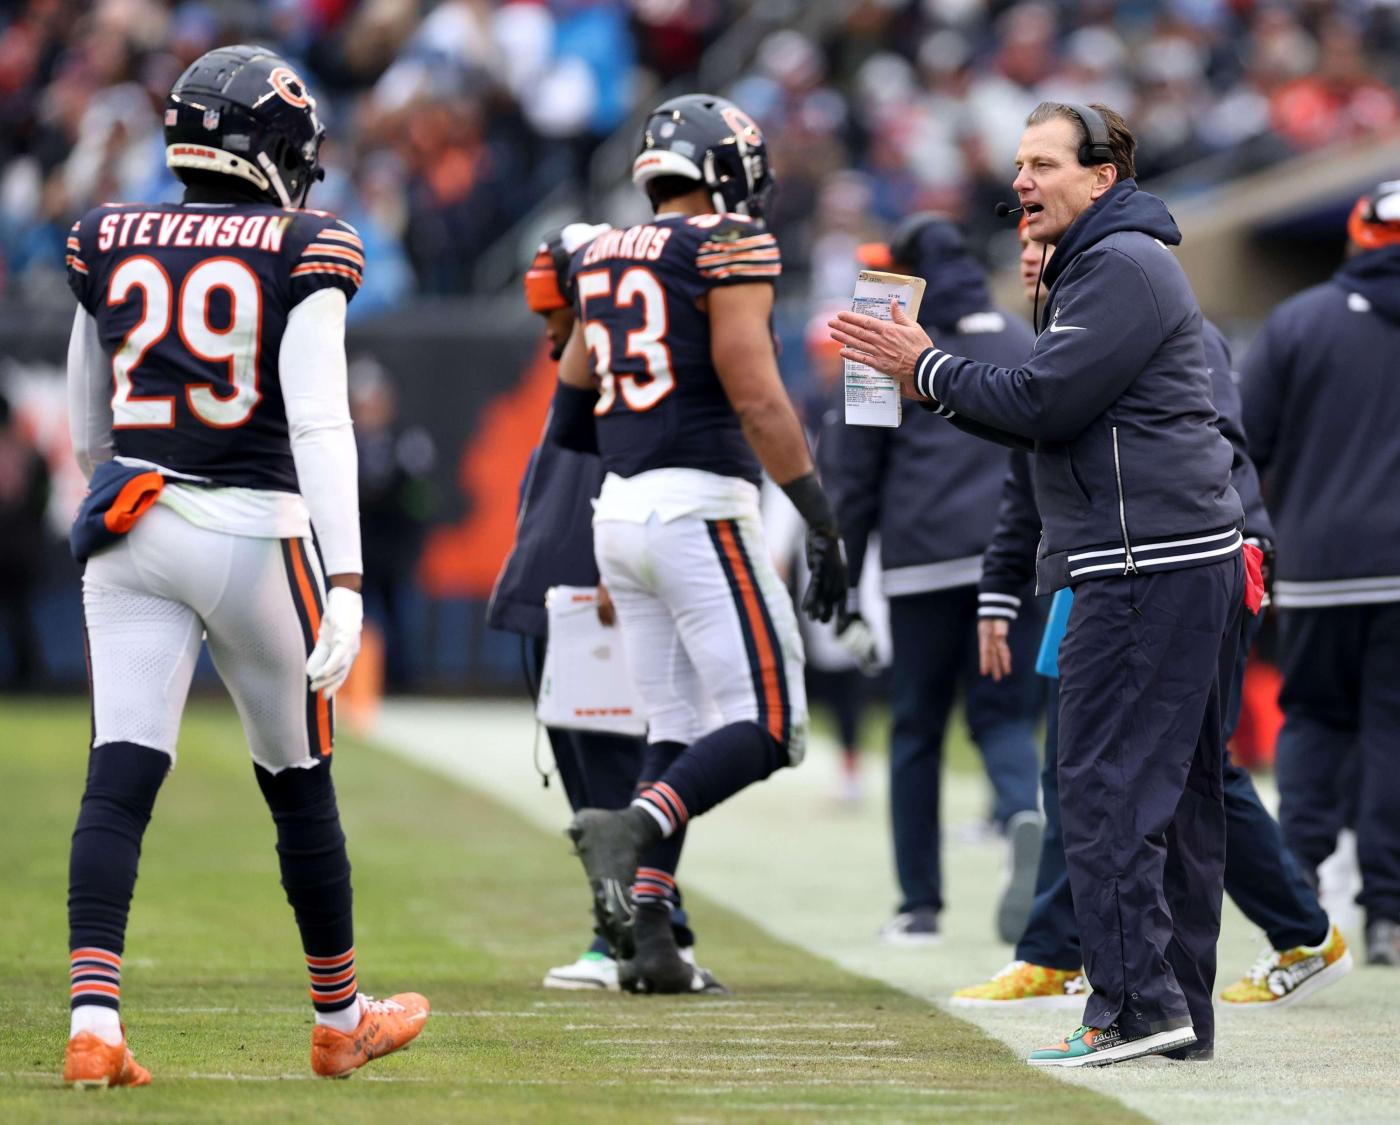
For the first time since September, Chicago Bears coach Matt Eberflus will have a separate defensive coordinator on his staff.

The Bears announced Saturday that they hired Buffalo Bills assistant head coach and defensive line coach Eric Washington to be their new DC. Washington previously coached with the Bears from 2008-10 under Lovie Smith and served as the defensive line coach in 2010 with defensive coordinator Rod Marinelli, an Eberflus mentor.

Washington coached the Bills defensive line since 2020 and was promoted to senior defensive assistant in 2022 and assistant head coach in 2023. He has two years of defensive coordinator experience with the Carolina Panthers in 2018-19 under Ron Rivera. Before that, he coached the Panthers defensive line for seven seasons.

The Bills defense ranked in the top 10 in multiple categories in 2023, including total yards and passing yards allowed per game, sack rate, interception rate and points allowed per game.

Washington is considered a strong teacher and leader who is detailed in his focus on fundamentals and will be able to help the coaching staff schematically, a source said.

“He is a great communicator with elite leadership skills and he will enhance our current defensive staff,” Eberflus said in a statement Saturday. “His track record speaks for itself with coordinator experience as well as expertise in the area of defensive line.”

Eberflus did not fill the defensive coordinator position in September when Alan Williams resigned for what sources told the Tribune was conduct-related reasons, though Eberflus did add senior defensive analyst Phil Snow to help scout opponents. Eberflus took over play calling, and with the help of the addition of defensive end Montez Sweat, helped the defense turn around from a rough start.

Eberflus said this month that he still was determining whether he would continue to call plays after bringing in a coordinator, but NFL Network reported Saturday that the expectation is Eberflus will remain in that role.

“It’s something I’ve stated I love to do,” Eberflus said this month. “But as we talk to these candidates, we’re going to keep everything open right now.”

Washington will help ease the load for Eberflus, who noted during the season he was working later nights to fill both roles. Eberflus said he was looking for a coordinator with high character who was a strong motivator. He wanted someone who could lead the defensive room while Eberflus addresses other areas of the team.

“My family and I are beyond excited to be returning to the Chicago Bears,” Washington said in a statement. “It is humbling to have the opportunity to contribute to one of the most esteemed sports organizations in the world.”

While the Bears fired five offensive coaches — including coordinator Luke Getsy — when their 7-10 season ended, Eberflus opted to keep the defensive staff intact. Washington joins a group that includes cornerbacks coach/defensive passing game coordinator Jon Hoke, defensive line coach Travis Smith, linebackers coach Dave Borgonzi and safeties coach Andre Curtis.

The Bears finished 12th with 324.2 yards allowed per game and had the top-ranked rushing defense, allowing just 86.4 yards per game on the ground. They also finished with a league-best 3.57% interception rate after totaling 22 interceptions to go with six fumble-recovery takeaways.

Their passing defense, ranked 25th with 237.8 yards allowed per game, and their league-worst 4.86% sack rate need improvement.

Washington joins what the Bears hope is an ascending group. He played tight end at Grambling State and also coached defensive line at Northwestern (2004-07) and Ohio (2001-03).

The Bears reportedly interviewed at least three other coaches to join their defensive staff: former Green Bay Packers defensive coordinator Joe Barry, Tennessee Titans assistant head coach/defensive line Terrell Williams and Titans defensive pass game coordinator Chris Harris.

Washington will be the Bears’ third major hire since the season ended. They have announced the

Wedding loans: How to finance wedding costs

posted in: Society | 0

Hanneh Bareham | (TNS) Bankrate.com

Whether you’d like a large, extravagant wedding or a small, casual affair, you may find yourself short on cash as you get deeper into planning out the details. This is where a wedding loan could be helpful in making your big day a dream come true.

Wedding loans make sense for some scenarios, but not all. Weigh the alternatives before jumping to a loan to ensure you’re starting your life with your new spouse on the right financial foot.

What a wedding loan is

A wedding loan is often a personal loan used to cover various wedding expenses, including the wedding venue, catering and a videographer.

A wedding loan is marketed toward engaged couples who are planning weddings. Some couples may use a wedding loan to finance certain parts of their big day, such as upgrading catering options, while others will use financing to pay for the whole event.

These loans are easy and quick to apply for — many lenders will even approve you online in a few minutes. The interest rate you’ll receive varies and is typically based on your income, credit score and current debts.

While some loans are marketed specifically as wedding loans, you’re generally free to use any type of personal loan to cover wedding costs, including home equity loans.

The cost of a wedding loan

How much a wedding loan costs depends on various factors, such as your loan term, interest rate and how much you want to borrow. You can use a personal loan calculator to easily determine how much your exact loan will cost.

The following table shows the costs of a three- and five-year loan with a 10 percent annual percentage rate.

3-year, $10,000 wedding loan at 10%5-year, 10,000 wedding loan at 10%

Monthly payments
$323
$212

Total Interest paid
$1,616.19
2,748.23

Total borrowing costs
$11,616.19
$12,748.23

When to get a wedding loan

It’s easy to get carried away planning the wedding of your dreams, especially with the constant influence of social media platforms. But it’s not advised that you take out a wedding loan unless it’s necessary.

When deciding whether to take out a loan, think about how crucial a larger budget really is. If you’re able to reduce costs in any way to better fit your available funds, then a wedding loan may not be necessary and you just saved yourself thousands of dollars.

Since wedding loans are unsecured, you don’t need to put anything up for collateral. While this reduces your personal risk, it increases the lender’s risk — meaning it is harder to get approved and get a competitive interest rate without a good credit score. But if you have excellent credit, you may be able to get a large loan at a low rate.

Pros and cons of wedding loans

When considering whether to finance your wedding, it’s important to consider the benefits and drawbacks before apply.

Pros of wedding loans

Soft credit checks: Lenders that offer wedding loans often allow you to prequalify so you can see the loan offers at your disposal without hurting your credit.
Potentially lower interest rates:Compared to credit cards, interest rates for wedding loans are usually lower and can save you thousands of dollars.
Longer repayment terms: Most wedding loans offer repayment terms of three to five years, so you can take your time paying your wedding off.
They’re unsecured loans: Since wedding loans are unsecured, you don’t risk losing your house, your car or any other asset you own if you’re unable to repay them.

Cons of wedding loans

Involve taking on debt: Wedding loans can steer you into a serious cycle of debt, especially if you already have other debt.
Interest rates can be high: If you don’t have a good credit score, you may have to settle for a high interest rate that can increase the overall cost of your loan.
Can lead to unnecessary spending: Wedding loans may lead you to spend on upgrades and extras you wouldn’t consider if you paid for your wedding with the cash you have on hand.

How to apply for wedding loans

To apply for wedding loans, follow these five steps:

Check your credit: Figure out where your credit stands by checking your credit score. If you don’t have the best credit, you may want to take steps to improve it before you apply for a loan.
Shop for lenders: There is no shortage of wedding loan lenders — from banks to credit unions. Check each lender’s credit requirements, funding times, loan rates and terms so you can determine which ones are a good fit.
Get prequalified: Many lenders offer a prequalification process that won’t impact your credit score and can give you an idea of the loans available to you. To prequalify, you’ll need to fill out a short form with your personal details.
Compare offers: Closely compare the wedding loan offers you receive. Consider interest rates, terms and fees. Choose the most favorable option that will save you the most money.
Apply: Once you decide on a wedding loan, complete the formal application. Most lenders offer quick approval for qualified applicants and typically deposit funds within a few business days or even 24 hours.

Alternative wedding financing options

If a personal loan isn’t in your wedding plan or you don’t think it’s the best fit for your situation, there are financing alternatives that may fit more comfortably into your financial portfolio.

Credit cards

Some credit cards offer an introductory 0 percent APR for a set period — typically between 12 and 24 months — after you open the account. This means you have time to pay off the balance without being charged interest.

A 0 percent APR credit card can be a great way to pay for vendor deposits and other immediate costs you can’t cover right away but can pay off in the next few months. Just make sure you can pay off the amount before the promotional period ends.

Personal savings

Try saving for a few years before a wedding. Dipping into a wedding-specific savings account you and your betrothed have will be better in the long run, since you won’t have to pay interest on loans or credit cards used to finance a wedding.

Ways to save

Create a budget: Look at your monthly income and expenses. Then, come up with a budget that works for your lifestyle needs and allows you to save for a wedding.
Take advantage of credit card perks: Many credit cards offer rewards such as cash back and points that you can redeem for free or discounted things such as airfare, lodging or gift cards.
Automate savings: Arrange for some of your paychecks to automatically go into your wedding savings account. This can allow you to save without much thought or effort.

Help from family members

Some family members may be willing to help you pay for a wedding. If a family member wants to help foot the bill for the big day, this is a good way to finance a wedding without having to get a wedding loan, use a credit card or dip into your own savings.

The bottom line

With the cost of an average wedding steadily climbing, fewer people can finance their big day out of pocket. Wedding loans are becoming more widely available due to demand and may offer more favorable interest rates than credit cards and other financing options.

But before you put yourself into debt, consider whether you need to finance wedding costs or if you can reduce the total price by making a few small sacrifices that won’t affect your experience. If you decide that financing a wedding with a personal loan is the right move for you, research and compare rates and fees from many lenders to find the best deal.

Key takeaways

• You could use a personal loan to cover several wedding costs, like a professional photographer or caterer.

• How much a wedding loan costs depends on various factors, such as your interest rate, repayment term and loan amount.

• Your eligibility for a wedding loan and how much you can borrow usually depends on your income, credit score and outstanding debt load.

• Before you use a personal loan to finance your wedding, consider alternatives, such as a credit card with a low APR promotional period or personal savings.

___

(Visit Bankrate online at bankrate.com.)

©2024 Bankrate.com. Distributed by Tribune Content Agency, LLC.