‘Monkey Man’ review: Patel impresses in front of, behind camera with revenge-fueled film

posted in: News | 0

Dev Patel clearly knew the comparisons to “John Wick” would be inescapable.

Thus, “Monkey Man,” his violent tale of a young man hell-bent on vengeance — inspired as much as anything, Patel says, by Korean action cinema — wisely namedrops the hit action flick starring Keanu Reeves that, to date, has spawned three sequels and a spin-off series.

Heck, there’s even a cute dog. (Don’t worry. It lives.)

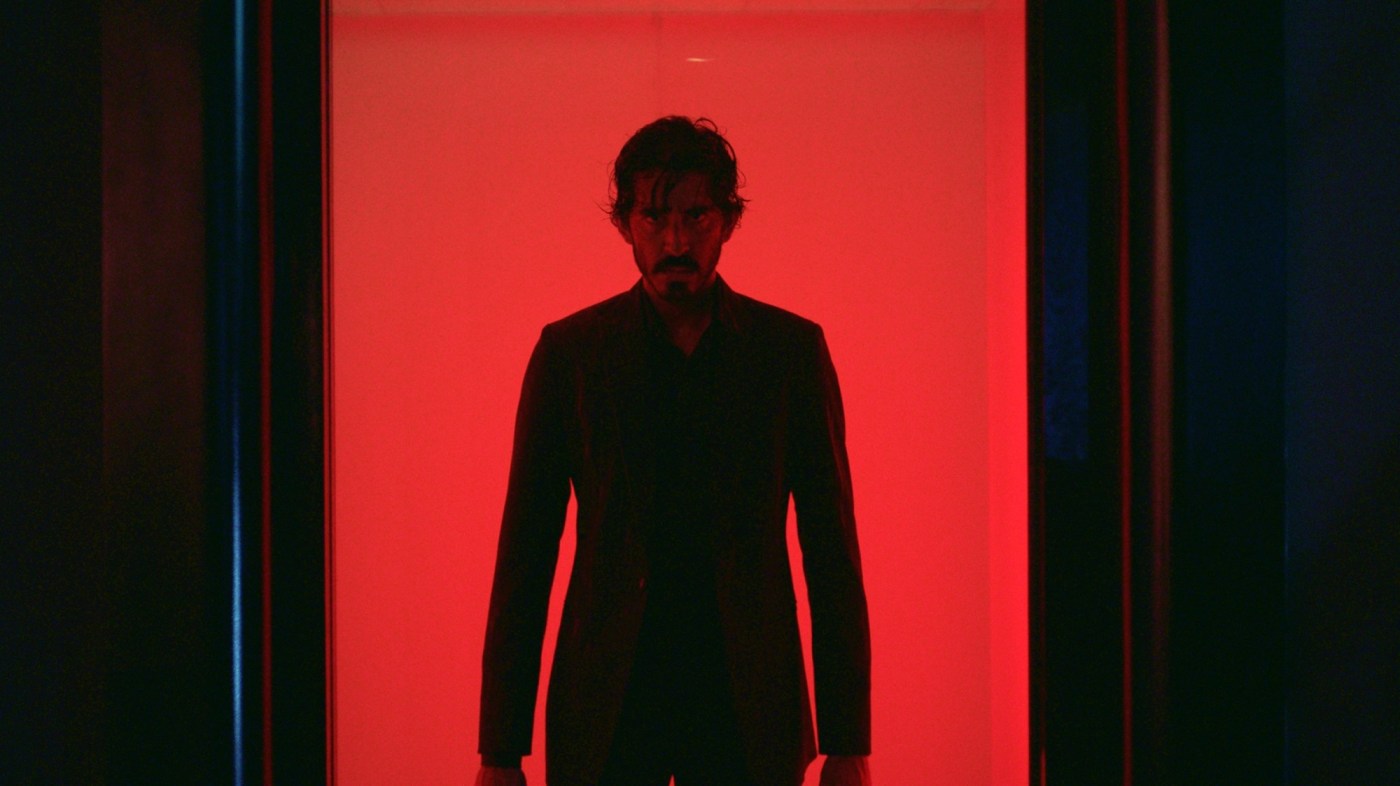
Patel makes a highly impressive debut as a director with “Monkey Man,” a film in which he also stars, serves as a producer and co-wrote. He also gets the lone story-by credit.

“Monkey Man” feels only so much like “Wick,” at least until its bloody, turn-your-head-at-times final act. If not quite grounded in reality, this film is based in something closer to it than what the “Wick”-verse has come to offer.

Plus, being set in modernized India — Batam, Indonesia, stood in for an Indian city during the film’s principal photography — and the incorporation of the Hindu deity Hanuman helps make “Monkey Man” more interesting from a cultural perspective.

We are introduced to Patel’s character, Kid, when he is a boy, being told stories of Hanuman by his loving mother, Neela (Adithi Kalkunte). We then cut to present day, as Kid — wearing a monkey mask as an homage to Hanuman — competes at an underground fight club run by the sleazy Tiger (a fun-as-always Sharlto Copley) to make ends meet. At this point in the story, Kid is a good enough fighter to put on a good show before taking a fall for some extra cash. (There’s even a “bleed bonus.”)

Sharlto Copley portrays Tiger in a scene from “Monkey Man.” (Courtesy of Universal Pictures)

Kid has his eyes on a different gig, any job within King’s Club, a high-end brothel. He gets his wish after a carefully orchestrated encounter with the ruthless, chain-smoking woman who runs it, Queenie (Ashwini Kalsekar). To execute his secret plan, he must get promoted and gain access to the VIP areas, so he befriends glorified gofer Alphonso (a consistently entertaining Pitobash) and soon is serving drinks to powerful men.

Related Articles


Review: Colin Farrell in Apple TV+ ‘Sugar,’ an LA story with a love-it-or-hate-it twist


‘Wicked Little Letters’ review: Punchy period piece powered by playful profanity


‘Godzilla x Kong: The New Empire’ roars to an $80 million box office opening


Review: ‘Godzilla X Kong: The New Empire’ is a worthy ‘When Hairy Met Scaly II’


‘Shirley’ review: Now on Netflix, the story of the first Black congresswoman on the ’72 campaign trail

And, oh boy, Kid does not like when those men lay their hands on the women the club employs to entertain them — especially the beautiful Sita (Sobhita Dhulipala).

Sobhita Dhulipala, center, portrays Sita in “Monkey Man.” (Courtesy of Universal Pictures)

However, he works to keep his eyes on the prize: corrupt police officer Rana (Sikandar Kher). (The reason Kid wants revenge on this man will become clear, as will the origin of the scars that cover our hero’s hands.)

When Kid moves against Rana — in a bathroom complete with a large aquarium — he meets more resistance than he’d bargained for and must run for his life.

To this point, Patel exhibits confident and skilled direction, “Monkey Man” boasting the kind of unusual camera angles and quick cuts — courtesy of director of photography Sharone Meir and editor David Jancso, respectively — that quickly could become exhausting if not handled so deftly.

All in all, this first act is downright stunning.

With the second, Patel over-course-corrects, giving the viewer a much-needed break from the action — especially considering what’s to come — as Kid heals among a group of people led by the wise Alpha (Vipin Sharma). It’s all a tad too snoozy, though — at least until the recovered Kid begins the obligatory training for the fight to come and is given tempo backing by an enthusiastic percussionist. (Hey, we think what we’re calling “bongo boxing” could catch on.)

Dev Patel’s Kid recovers from the initial battle in a scene from “Monkey Man.” (Courtesy of Universal Pictures)

The final chapter of “Monkey Man” delivers the high body count for which we’d been waiting. As nifty (and disturbing) as many of the mini sequences are, “Monkey Man” becomes a bit numbing in the way similar action movies can.

In front of the camera, Patel is a compelling lead, which is no surprise given past films such as “Slumdog Millionaire” (2008), “The Best Exotic Marigold Hotel” (2011) or “Lion” (2016). However, Kid is a far cry from the gentle souls he played in those films. He is out to conflict pain and suffering on those he believes deserve it, and Patel sells it convincingly, down to the muscle he added at some point.

Dev Patel’s Kid channels the path on his quest for vengeance in “Monkey Man.” (Courtesy of Universal Pictures)

Originally, “Monkey Man” was bound for a streaming platform, before gaining the attention of Monkeypaw Productions, the company founded by filmmaker Jordan Peele (“Get Out,” “Nope”), and shifting to a theatrical release. This is a film worthy of a big screen.

And given its strengths, it’s more than worthy of a follow-up. That said, there’s something at least a little special about this one, and we wouldn’t mind if it doesn’t lead to, say, three more movies and a TV series.

‘Monkey Man’

Where: Theaters.

When: April 5.

Rated: R for strong bloody violence throughout, language throughout, sexual content/nudity and drug use.

Runtime: 2 hours, 2 minutes.

Stars (of four): 3.


‘Scoop’ review: Prince Andrew in the hot seat

posted in: Politics | 0

In 2019, Prince Andrew sat for a one-on-one with the BBC program “Newsnight” to discuss his connections with Jeffrey Epstein, who had been found dead in his jail cell three months earlier. The Netflix movie “Scoop” is the story of how the now-infamous interview came about. The TV appearance would prove to be such a public relations disaster that Andrew stepped down from royal duties shortly thereafter. For many viewers, he failed to give a persuasive refutation of the allegations made against him, or to adequately explain his friendship with Epstein, a convicted sex offender who was being held on sex trafficking charges at the time of his death.

It has been a rocky year for the British monarchy and the comms teams employed to manage its messaging. This is yet one more story that won’t go away, much as the royal family may wish it would. In 2022, Andrew agreed to an estimated £12 million settlement with Virginia Giuffre, who alleged she was forced — via Epstein — to have sex with Andrew when she was a teenager. But it was the “Newsnight” interview that played a key role in forcing the institution’s hand: Andrew had become too much of a liability.

Related Articles


Review: Colin Farrell in Apple TV+ ‘Sugar,’ an LA story with a love-it-or-hate-it twist


‘Ripley’ review: A remake of ‘The Talented Mr. Ripley’ has a terrific performance at its center, but lacks heat


Movie review: ‘Housekeeping for Beginners’ a riveting domestic tale of blended queer family


Movie review: ‘Godzilla x Kong: The New Empire’ an earnest, wacky, hectic ride


‘Shirley’ review: Now on Netflix, the story of the first Black congresswoman on the ’72 campaign trail

In theory, the behind-the-scenes negotiations led by Sam McAlister, the “Newsnight” producer who landed the interview (and would later write a book about it), should be compelling. But there’s nowhere near enough story to justify a movie-length depiction. It’s as if someone pitched this as the UK version of “She Said,” but none of it feels pressing or as high stakes as it should. Writing for Tatler ahead of the Netflix premiere, McAlister calls Andrew’s interview a “masterclass in how to destroy your life.” If only the movie itself felt as dramatic as that description.

Maybe British audiences will get something meaningful from this exercise — and read something between lines that non-British audiences won’t — but either way, “Scoop” would have benefited from more rigorous introspection about the nation’s strangely deferential relationship to its royal family, and why Andrew’s situation has been so uniquely odd. Consider this past weekend: Despite his supposed ostracization, he was alongside his siblings this Easter, an annual tradition that is photographed and publicized and therefore doubles as palace PR. What are we meant to read into that? Is it a shrug — or worse, a middle finger — to the film? To anyone who takes the allegations seriously?

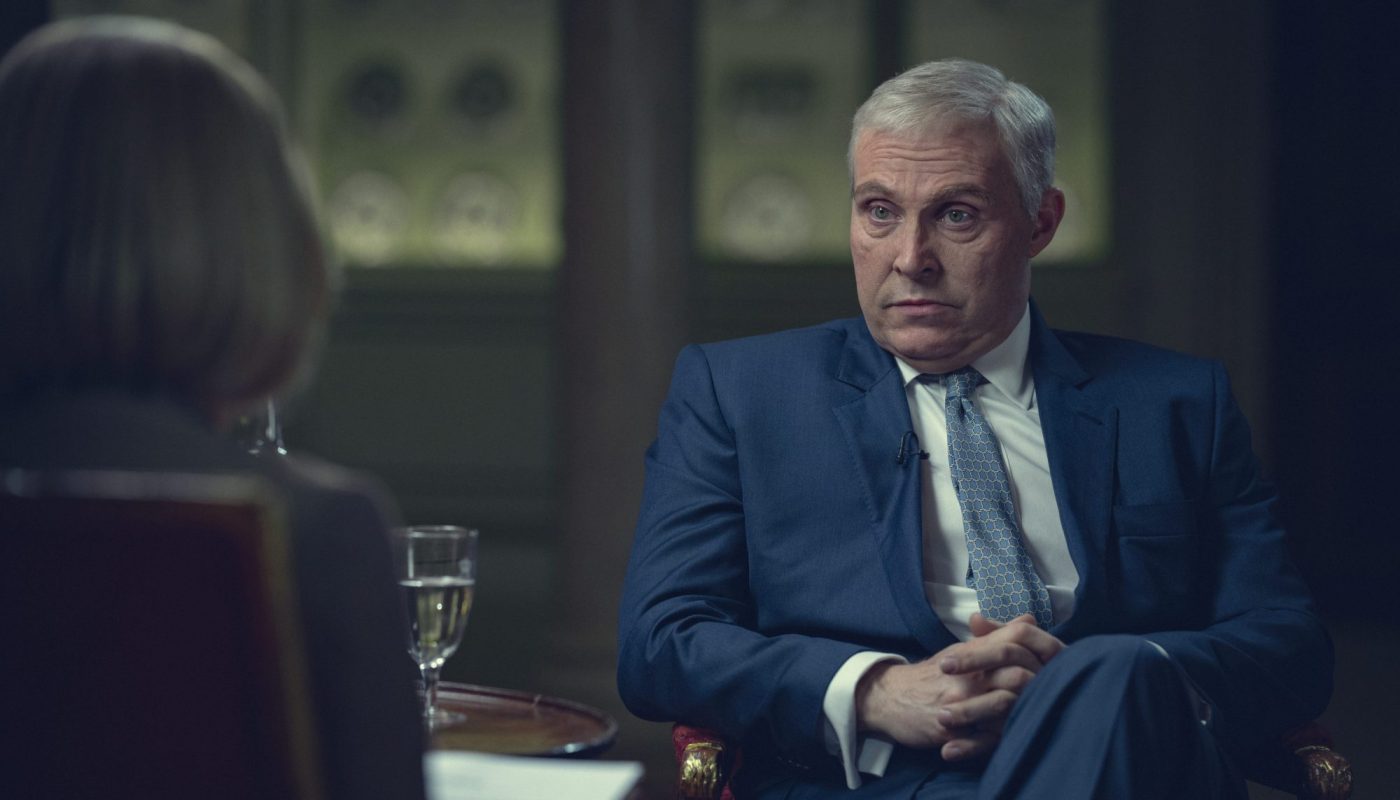
A movie like “Scoop” raises as many questions as it attempts to answer. Royals rarely agree to be grilled on camera. So why did Andrew — and why did Queen Elizabeth II allow it? Maybe it was hubris. Here was a man who moved through life seemingly without any consequences for his actions, and a powerful parent who enabled that. How dare the media remind people of those times he consorted with Epstein? Surely his powers of persuasion would be enough to put this to rest once and for all. As played by Rufus Sewell, the voice is too pinched and high, but he’s believably sputtering and pompous and foolish. This isn’t a new insight, though.

According to “Scoop,” McAlister gets the interview through some fairly basic tactics: She lays the groundwork with Andrew’s top aide (a scared mouse played by Keeley Hawes), telling her: “You can’t go ‘no comment’ on being friends with a pedophile and expect everyone to love you, no matter who you are.”

As played by Billie Piper, Sam is styled as if she were an extra from “Working Girl” who wandered on set decades after the fact. The subtext is clear: She doesn’t fit in with her posher colleagues at the BBC. But what’s missing are frank observations — debates even — about Britain’s class system and how that affects news coverage. The script is from Peter Moffat and Geoff Bussetil, and Moffat in particular has done sharper work in the past, particularly as the creator of the legal drama “Silk.”

A major sticking point is that none of these characters have been developed into people who are interesting enough to carry what is ultimately an exceedingly thin story, and the lack of intrigue becomes a glaring issue. The actual “Newsnight” interview conducted by a steely Emily Maitlis (played by Gillian Anderson) is available online in full. Recreating it serves no purpose; it’s neither dramatically interesting, nor does it plumb deeper insights into the media or the powerful people it covers.

Less than two months after the interview aired, it was reported that Andrew’s aide had accepted an exit package “worth tens of thousands of pounds” (a detail not included here). And McAlister herself, who has since left her job at the BBC, told a British newspaper last year that she wrote the book, in part, because “if Netflix ever makes a future edition of ‘The Crown’ or a documentary on Prince Andrew, I want my role on the record.” According to that same story, her former colleagues are “quietly seething at what they perceive to be McAlister taking the lion’s share of credit.”

It’s McAlister’s recent piece in Tatler that underscores where the movie goes wrong. “Fifteen feet,” she writes. “That’s how far I was from the back of his chair. I could see the soles of his shoes (hardly scuffed), the back of his head (new haircut), the bottoms of his trousers (tailored to a perfect length), the jacket (ill-fitting, remarkably) and the nervous movement of his left foot as it tap-tap-tapped, over and over, against the ornate carpet on the floor. The chair itself was also ornate, but it seemed very small with Prince Andrew sitting in it, as he moved nervously from side to side, awaiting his fate.”

None of these details add up to anything but a vaguely awe-struck moment and the ability to capture what “Newsnight” audiences already saw with their own eyes.

“Scoop” — 2 stars (out of 4)

Where to watch: Netflix

Nina Metz is a Chicago Tribune critic.

How to protect your deceased loved one’s credit after death

posted in: News | 0

Ashley Kimler | (TNS) Bankrate.com

Grieving the loss of a loved one is an emotionally and mentally challenging experience. Still, amid the turmoil of the grieving process, it’s essential to address the deceased’s financial matters and protect their credit information. Requesting a credit freeze is a crucial first step.

By following this process, you can safeguard their financial status and protect yourself and other loved ones from potential fraud or identity theft.

Why a credit freeze is necessary after a loved one’s death

A credit freeze is like a lock on someone’s credit report, making it harder for identity thieves to use their information for fraud.

When a loved one passes away, their financial details become vulnerable. Freezing their credit will:

—Prevent identity theft

—Prevent new accounts from being fraudulently opened under their name

—Protect sensitive information

Without a credit freeze, the deceased’s personal data, such as their Social Security number (SSN), could be stolen and used to open credit cards or other financial accounts. Some criminals use obituaries, death certificates and other information to steal the identities of people who have died. They might open new accounts or commit other crimes under the deceased’s name, causing problems for living relatives.

Freezing credit makes it much tougher for thieves to open new accounts or misuse existing ones.

How to report a death to the credit bureaus

Initiating a credit freeze for a deceased loved one involves a few straightforward steps:

1. Gather your loved one’s personal details

Before you notify the credit bureaus of a loved one’s death, you’ll need to collect certain information and documentation:

—The complete legal name of the deceased individual as it appears on official documents.

—The deceased person’s SSN, which is crucial for identifying their credit file.

—The date of birth of the deceased individual.

—The date when the individual passed away.

—A copy of their death certificate.

Your own identification may also be required if you’re the spouse or shared a credit file with the departed.

If you’re not the spouse, you may need to submit proof that you’re authorized to act on behalf of the deceased, such as a copy of a will, executor agreement or power of attorney documentation.

Having this information readily available will ensure a smooth and efficient process when you contact the credit bureaus.

2. Write letters to notify the credit bureaus

The three major credit bureaus, Transunion, Equifax and Experian, must be notified of the death. The first bureau you contact will notify the other two on your behalf.

However, one bureau cannot necessarily initiate a credit freeze across all three bureaus. So, you should contact all three bureaus and send copies of all necessary documents with each letter.

Use this simple template to notify the credit bureaus of your loved one’s death and request a credit freeze:

[Your Name]

[Your Address]

[City, State, Zip Code]

[Your Phone Number]

[Date]

[Credit Bureau’s Name]

[Credit Bureau’s Address]

[City, State, Zip Code]

Subject: Notification of Death and Request for Credit Freeze

To whom it may concern,

I am writing to inform you of the passing of [Name of Deceased], [relationship to you, e.g., my spouse]. [He/She] passed away on [Date of Death]. I kindly request that you freeze [his/her] credit report to prevent any potential fraud or unauthorized access.

Enclosed is a copy of [Name of Deceased]’s death certificate as proof. Please freeze [his/her] credit report and mark it as “deceased — do not issue credit.”

I would also like to request a final copy of [Name of Deceased]’s credit report for my records.

Thank you for your prompt attention to this matter. Please confirm with me when you have received the notification and that a credit freeze has been placed.

Sincerely,

[Your Name]

You can customize this template and include any information appropriate to your situation. Be sure to save a copy for your records.

Once you’ve drafted your letter, you can send it to one or all of the major credit bureaus via postal mail. Be sure to attach copies of identifying documents and send each letter via certified mail.

Appropriate contact addresses for notifying credit bureaus of a death are as follows:

Transunion, P.O. Box 2000, Chester, PA 19016

Experian, P.O. Box 9701, Allen, TX 75013

Equifax Information Services LLC, P.O. Box 105139, Atlanta, GA 30348-5139

Times for the credit freeze may vary. Transunion will update the individual’s credit report within five days of receiving the documents and send you a confirmation letter. Experian will add a death notice to your loved one’s credit report upon receiving notification from the Social Security Administration or the requestor. Equifax will add a death notice to your departed’s credit report upon receiving the documents.

3. Confirm the freeze and ensure the account is flagged as deceased

After sending your request to the credit bureaus, confirm that they have initiated the credit freeze and properly flagged the deceased individual’s account:

—Allow some time for the credit bureaus to process your request. This typically takes a few days or up to a couple of weeks.

—Reach out to each of the three major credit bureaus — TransUnion, Experian and Equifax — either via phone or online.

—Ask them to verify that they have received your request to freeze the deceased individual’s credit report.

—Ask if the deceased’s account has been appropriately flagged as “deceased — do not issue credit” to protect their information from potential fraud.

5. Request a copy of your loved one’s credit report

While you are in contact with the credit bureaus, you should also request a copy of your loved one’s credit report. This will confirm that the report has been marked “deceased” and that a permanent credit freeze is in place.

You can also use the credit report to assess your loved one’s financial standing. Read the credit report carefully to identify any discrepancies and all outstanding accounts, and note any accounts that need your attention.

How to settle your loved one’s financial affairs

Once you’ve taken steps to freeze credit, it’s important to deal with your loved one’s outstanding financial obligations.

You might inherit some of their debts if you’re their spouse or beneficiary. Whether you’re on the hook to repay those debts depends on the terms of the accounts and your state’s laws. In some cases, a transfer of debt responsibility upon death is unavoidable.

For instance, if you jointly held debts with your loved one, like mortgages or shared credit card accounts, you could be responsible for them, no matter who made the charges. Similarly, if someone cosigned a loan or credit card for the deceased, they’ll be responsible for that debt.

If the deceased had a home equity loan on an inherited house, the heir would have to repay it. Timeshares and their maintenance fees will also fall on heirs if their names are on the deed.

Family members who authorized medical treatment may have to pay any uncovered medical bills, depending on state laws and document terms.

Contact your loved one’s creditors to:

—Close accounts

—Manage tax paperwork

—Settle outstanding balances

In some situations, accounts may be closed automatically when a person passes away. However, some accounts may still require settlement, either partially or fully, even after the account holder’s death.

The bottom line

A credit freeze for a deceased loved one is a crucial step to safeguard their financial legacy. By taking the right steps and organizing important documents, you can safeguard their private information and handle financial matters with minimal stress.

Take each step with care — and seek professional assistance if needed — to honor your loved one’s financial well-being even after they’re gone.

Frequently asked questions

—How do you close your dead relative’s accounts?

Make multiple copies of the death certificate and notify each of your relatives with this proof. Request account closure and settle any past-due balances when necessary. Monitor your relative’s credit reports for fraud while you’re waiting for a credit freeze to take effect with the bureaus.

—Do you need to notify the IRS when someone dies?

Yes. When someone dies, you or the appointed representative need to file the deceased person’s final tax return. On this return, you must indicate the person’s death. At present, the IRS doesn’t require any other notification of the death, but you should always look to irs.gov for up-to-date tax information.

—Can a credit freeze be lifted temporarily, such as for estate-related transactions?

A credit freeze can be temporarily lifted upon request. However, lifting a freeze can expose the account holder’s credit information to fraud risk.

(Visit Bankrate online at bankrate.com.)

©2024 Bankrate.com. Distributed by Tribune Content Agency, LLC.

No retirement fund? Stop saying yes to frivolous spending

posted in: News | 0

When thinking about retirement, should I be selfish with my money?

If you are saving monthly, have cash in the bank, no or minimal debt, and plan accordingly for your retirement, then this article may not interest you.

But, if you spend money freely, have high credit balances, and never place much thought on your future. It may be time to change your behavior, learning that it is okay to say “no” to spending money and placing your interests first.

According to a November 2023 survey by Bankrate, 49 percent of credit card holders carried debt from month to month, and in 2022, 23 percent of Americans had no emergency savings.

Unfortunately, we live in a world of consumerism. If you do not live in a lovely home, drive a nice car, or dine at first class restaurants, you may feel like a failure. But often, there is not a direct correlation between wealth and the image we present to our friends and family. Just because someone is perceived as successful, it does not mean they have acquired wealth or are prepared for retirement.

Are you:

—Always stressed about money

—Struggling to pay your bills

—Relying on credit to carry you through the month

—Wondering why you do not have any money

—Giving money away to adult children, family members, or friends

—Shopping in secret and hiding your purchases

—Dining at expensive restaurants that you cannot afford

If you do not understand how and where you are spending your money, it may be time for you to evaluate your finances and begin to plan for your future.

Are you saving for your retirement?

People can live 10, 20, or even 30 years in retirement. If you have a pension, it may not be much of a concern because you will have an income stream. But most people do not have a pension and need to rely on their savings and social security benefits for income.

Understand how much you will need to save before you retire so you can transition into retirement without reducing your standard of living. If you do not know where to start, a Certified Financial Plannercan help you by running projections to estimate how much you will need to have saved prior to retirement to align with your current living standards.

Conventional wisdom dictates that you should plan to withdraw 4% (adjusted annually for inflation) for about 30 years from a portfolio that is invested 60% in stocks and 40 percent in fixed income. This is a basic rule, and the distribution amount is often much lower than people anticipate.

For an individual who has $1,000,000 saved, under this rule, $40,000 year one is a safe withdrawal rate. The amount you should withdraw will depend on many factors, such as age, net worth, portfolio allocation, and the current economic circumstances. Depending on your situation, the annual withdrawal rate could be lower than 4 percent.

Are you budgeting?

A budget is a personal plan to manage your money. It provides the opportunity to identify and monitor your spending. Simple as it may be, it is the foundation for sound money management.

Budgeting begins with monitoring a specific period, such as a month. It requires that your income and all of your spending is tracked during this period. It records fixed expenses, as well as the simple purchases we often forget, such as a quick bite to eat.

At the end of a period, your budget provides a transparent snapshot of your income and where you spend your money.

The key to budgeting is to understand if you have a monthly shortfall or surplus to determine what changes you can make to improve your financial outlook now that will positively impact your retirement.

Do you have credit card debt?

If you are using credit because you are living beyond your means, this is a red flag with the potential of having a detrimental outcome in your future. Evaluate what you can do now to make paying off your debt a priority. Find a payment strategy that works for you, such as the snowball or avalanche method.

This also means that you will need to change your behavior and spending habits. Find areas in your lifestyle where you can easily eliminate the expense by changing your actions, such as eating out less, not shopping online when you are bored, or finding inexpensive activities to engage in when spending time with family and friends.

Review your credit statements monthly to know what the interest rate and balance is on the outstanding debt. And if you do not think you will have the willpower to stop using your credit cards, take them out of your wallet and place them in a safe place. Then delete the credit cards from on-line sources you may be tempted to use. So, in a weak moment, they are not readily available.

When you apply for a credit card, a loan, or insurance, a file is created on you. This file is managed by credit reporting companies, and the information is called your credit report.

Your payment history and the amount of credit that you have are tracked over your lifetime. Credit history is important; without a credit score above 720, it is difficult to finance the purchase of a home. Credit card reporting agencies know that when a consumer carries high credit card balances, their default risk increases, and the agency will penalize the consumer by lowering their credit score.

What are you short and long-term goals?

Identifying your short-, mid-, and long-term goals and objectives, as well as the impact obtaining them will have on your finances is key to a successful future, and eventually retirement.

Short-term goals could include budgeting, reducing debt, and establishing an emergency fund.

Mid-term goals may be to buy a new car or save for a down payment for a new home, while long-term may be planning for your retirement. When you do not plan for your goals, you may find yourself in a financial position that is not ideal.

Planning prepares you for the future and eliminates the stress and additional expense from poor impulsive financial decisions.

If you are not currently preparing for your retirement, then it may be time to learn to say “no” to yourself, children, family, and friends when it comes to spending money that is not in your best interest. You do not need to elaborate as to why and can easily defer to your budget. The simple answer could be, “It is not in my budget this month.”  Then take a deep breath and exhale because you have taken the first step to financial freedom.

Teri Parker CFP® is a vice president for the Riverside office of CAPTRUST Financial Advisors and has practiced in the field of financial planning and investment management since 2000. Contact her at Teri.parker@captrust.com.

Related Articles

Business |


How to protect your deceased loved one’s credit after death

Business |


How to buy life insurance in 8 steps

Business |


Fix your fixer-upper pre-sale, this company says, and quit leaving money on the table

Business |


Retirees: Is it time to downsize, even in this real estate market?

Business |


House hunters fear Realtor settlement could make homebuying harder