Q4 data: Home buyers chilled by high prices and rates

posted in: Society | 0

By Elizabeth Renter | NerdWallet

In the last quarter of 2023, home sales were few and far between as high prices, high rates, low inventory and seasonal factors all combined to make the housing market a bit of a ghost town. Would-be first-time buyers no doubt felt the desolation.

Homes were listed at nearly five times the potential first-time buyer income in the fourth quarter, on average across the country. Prices fell slightly from the previous quarter, as is common in the final months of the year. Bucking seasonal trends, inventory rose 9% from the third to the fourth quarter, reaching a level not seen since late 2020. But mortgage rates peaked in late October, hitting about 7.8% for the 30-year fixed, an over-two-decade high, before trending downward through the holidays.

First-time buyers have to contend with unique challenges no matter the market. They are generally earlier in life and career than repeat buyers, and they lack the wealth associated with equity that existing homeowners can draw upon.

In 2024, rates have already begun to come down and are expected to reach 6% by the end of the year. While this will provide some relief in the costs of ownership, the year is unlikely to bring much in the way of lower prices or meaningfully higher inventory.

Seasonably slightly lower prices in fourth quarter

Home prices typically come down slightly as the weather cools, and inflation-adjusted list prices were 4% lower across the nation in the fourth quarter. List prices matter because they likely play a significant role in would-be home buyers’ decisions to get serious about home shopping.

Related Articles

Business |


6 ways to save money in Paris during the Olympics

Business |


Wedding loans: How to finance wedding costs

Business |


Managing credit cards when you grew up in a cash-only household

Business |


Millennials, it’s time to change your investment strategy

Business |


6 ways to spring clean your bank accounts

Comparing list prices versus the median income of people in the typical first-time buyer age range provides a good gauge of affordability. And while homes were listed at 4.9 times this income across the nation, the largest metros demonstrated that buyers shouldn’t necessarily base their decisions on national numbers.

One of the most affordable metro areas, Pittsburgh, had homes listed at 2.9 times first-time buyer income. It’s the only metro area where the metric came in below an old rule of thumb — that homes listed at three times your income are likely to be affordable. Other affordable metros include Cleveland and Detroit, where homes were listed at 3.3 times first-time buyer income; and St. Louis and Buffalo, New York (3.5).

At the other end of the spectrum, homes in Los Angeles were listed at 12.8 times would-be first-time buyer income. Other costly metros include San Diego (10), Miami (8.4), San Jose, California (8.1), and New York City (7.6).

First-time buyer guidance: Prices are unlikely to come down meaningfully in the coming months; they generally rise as we move into the second quarter. Steady yourself for the reality of the high prices you’ll face in the market where you hope to buy. A local real estate agent can provide intel beyond the list prices you see in real estate apps on your phone. They can tell you whether homes in your area are selling for over list price and how many offers they’re getting, on average.

Mortgage rates peaked

Affordability depends on more than list prices, and rates impacted even the most affordable markets. With interest on a 30-year fixed mortgage averaging 7.3% in the fourth quarter, the monthly principal and interest payment on a median-priced home would be about $2,290, assuming a 20% down payment. By contrast, if rates were a percentage point or so lower — where projections show them going by the end of 2024 — that monthly payment would be nearly $300 less.

The costlier the home, the more these higher rates matter. For example, payments on a median-priced home in Cleveland would be nearly $160 less at 6% than 7.3%, while payments in San Jose, where typical home prices exceed $1 million, would be about $920 lower under that more favorable interest rate.

First-time buyer guidance: Rates are projected to decrease modestly throughout 2024. To qualify for the lowest rates, you’ll want to keep your credit in tiptop shape. This should be a long-term goal as well — if rates decrease after you’ve purchased, having solid credit can help your chances of refinancing your mortgage to take advantage of those lower interest costs.

Fourth-quarter inventory continued (slowly) recovering

The number of homes available for sale has been paltry for several years now, falling to fewer than 400,000 across the country in 2022, compared with more than a million in late 2019. And while listings are generally at a low point in the fourth and first quarters of the year, there were more homes on the market in the last quarter of 2023 than in Q3. In fact, inventory rose 9%, to a level not seen since late 2020.

Across the most populous metros, inventory rose nearly across the board, spiking highest in Tampa, Florida (+34%), Phoenix (+30%), Louisville, Kentucky, and Miami (both +25%).

First-time buyer guidance: Though inventory is beginning to rise and we’ll likely see more homes hit the market as the weather warms and rates continue to fall, there is still a serious shortage. This means competition will be fierce for the listings that are available. Go into the housing market with a game plan — a detailed shopping list, of sorts. You’ll likely have to sacrifice some of the items on your wish list, but knowing which you’re willing to compromise on beforehand can make those compromises less hand-wringy.

The analysis methodology is available in the original article, published at NerdWallet.


Elizabeth Renter writes for NerdWallet. Email: elizabeth@nerdwallet.com. Twitter: @elizabethrenter.

Why was my mortgage application denied? Common reasons underwriters don’t approve loans

posted in: Society | 0

Jeff Ostrowski | (TNS) Bankrate.com

For borrowers in a still-hot housing market, getting approved for a mortgage can be a challenge. Mortgage rates have soared from pandemic-era lows, home values are near record highs and home price appreciation is outpacing wage growth.

All of that means there’s no guarantee a lender will approve your mortgage application. Here’s a look at how lenders decide to extend credit, and some common obstacles borrowers face.

How does mortgage underwriting work?

Mortgage underwriting is the process of verifying and analyzing the financial information you provide your lender — all with the goal of giving you an answer of yes, no or maybe. As part of the application, you produce bank statements, W-2s and other tax documents, recent pay stubs and any additional documentation the lender requires or requests.

Dispense with any stereotypes about the old days of lending or the movie It’s A Wonderful Life, when a banker determined your creditworthiness by the firmness of your handshake and the crispness of your shirt. In most cases, a loan officer or mortgage broker will collect your information and submit it to an underwriting software system — Desktop Underwriter for a loan that will be sold to Fannie Mae, Loan Product Advisor for Freddie Mac.

These systems don’t allow for much in the way of human judgment — the software determines whether you’re either approved, rejected or asked for additional information. Such automated underwriting, as it’s officially called, is the norm nowadays — part of the reforms to the mortgage financing world developed after the 2007-09 mortgage meltdown and subsequent financial crisis. “Prior to the crisis, there was more leeway,” says Bill Banfield, chief risk officer at Rocket Mortgage. “Now, most of that subjectivity is gone.”

There are many reasons — income, or property type, or something else — that the automated underwriting process might flag your application. And if it does, there’s little the human loan officers can do about it.

Keep in mind: The main thing the lender decides is your mortgage’s interest rate. And of course, how much to charge you in fees.

Reasons a mortgage loan is denied

“There’s a thousand potential questions Fannie [or Freddie] could return,” says David Aach, chief operating officer at Blue Sage Solutions, a mortgage technology firm. “That’s the nightmare of the underwriting process.” Here are some of the more common reasons you might not get approved for a mortgage.

1. You have credit issues

Your credit score is the single most important factor in determining your mortgage rate — and whether you get approved at all. Generally, the best deals go to borrowers with credit scores of 740 or above, and ones in the “good” range — 670 to 739 — are the most desirable.

Still, you can qualify for some types of mortgages with much lower scores. For instance, VA loans generally are available to borrowers with scores of 620 or above, white FHA loans go to those with scores as low as 580.

Before applying for a mortgage, check your credit score and credit report and dispute any errors. If your credit score is low, work on boosting it before you apply (for example, you could ask a card company to increase your credit line, which automatically lowers your credit utilization ratio). If you have a qualifying credit score, make sure you don’t do anything during the mortgage process to cause it to drop, like miss a payment or max out a credit card, or apply for some other big new loan.

If you don’t have a credit score at all, some lenders do have alternative credit scoring methods, such as analyzing your bank deposits. In fact, last year Fannie Mae updated Desktop Underwriter to take into account a loan applicant’s financial and investment accounts, as an alternative to an absent credit score or incomplete credit history.

2. You have an income shortfall

Your debt-to-income (DTI) ratio — the portion of your gross (pre-tax) monthly income spent on repaying regular obligations — signals to lenders whether you’re in a position to take on an additional, major debt. If your DTI is too high, you may be rejected for a mortgage. Most lenders require a DTI of less than 43%, with 50% the max.

Aim for your obligations comprising about one-third of your income: A DTI around 36% is the ideal, qualifying you for better loan terms. If you owe a lot in student loans, car loans or credit card balances, work on bringing those balances down before applying for a mortgage.

Also give a thought to the type of loan: The longer its term, the more affordable its monthly payments. So opting for a 30-year mortgage might boost your chances, even though you’ll pay more in interest over its lifespan, compared to shorter-term loans.

On the income side, issues often emerge when the mortgage applicant is self-employed. In the first place, the software is geared to good old W-2s — that wage-and-tax-statement from an employer — and gets uneasy when an income stream is irregular, even if your earnings are high.

Also, business owners often maximize write-offs and expenses when doing their taxes — but that common practice flummoxes the underwriting models.“Self-employed people know what they make, but they don’t know what an underwriter is looking for,” says Tom Hutchens, executive vice president at Angel Oak, a lender specializing in non-QM loans (mortgages outside the conventional criteria). “They might be fully approved, but then an underwriter looks at the tax returns” and sees that “$10,000 a month might become $5,000 a month in income.” The lower amount upsets the software, which then dings the applicant.

3. The loan-to-value ratio (LTV) is too high

Lenders also look at how much of a mortgage you want, vis-à-vis the value of the home you’re buying — something called the loan-to-value ratio (LTV). The bigger your down payment, the less you borrow, and the lower your LTV. For instance, if you’re buying a $400,000 house with a down payment of $80,000, your LTV is a comfortable 80%. (While there’s no single perfect percentage, lenders usually like to see it around this amount — for conventional loans, anyway.) But if you’re putting down $20,000, the LTV is up to 95%.

The higher your LTV, the more likelihood that your loan will be flagged for follow-up questions, or rejected altogether. If you feel you need help lowering your LTV, look into down payment assistance — every state has these programs, especially for first-time buyers — to increase the amount of cash you can bring to the deal.

4. You’re trying to finance an out-of-favor property

Not all homes are created equal, as far as lenders are concerned. The traditional, detached single-family residence still rules, and alternatives can confound.

Condos are one particularly tough type of home to finance. In response to the June 2021 collapse of an oceanfront tower near Miami, Fannie and Freddie rolled out new rules covering condo loans: The giant mortgage market-makers have decided not to finance some buildings that have low reserves, need repairs, or are facing lawsuits. Critics say the stricter reviews are causing condo sales to fall apart, even in buildings with no structural issues.

Manufactured homes also can be challenging to finance. And if appraisers or inspectors find a structural flaw or other issue with the home itself, that also can slow the approval, or even kill it.

5. Something recently changed in your financial life

The lending process prizes financial stability and predictability(remember what we said about income, above). And while the job market was still going strong as of early 2024, many Americans have changed positions, either by choice or by necessity. Unfortunately, a recent job change or period of unemployment can throw a wrench in your approval. A short employment history or interruption in earnings sends warning signals to the software.

Unusual activity in your bank account can be another issue. Underwriters are skittish about large, unusual deposits, which might mean you borrowed money for your down payment. If you got money from relatives to help you buy a house, make sure to submit a gift letter as part of your application.

How to get a mortgage after your application is denied

Take heart: If you are denied a mortgage, all is not lost. There are workarounds to many of these issues.

If you have a unique income situation, such as owning a business with unsteady cash flow, you might apply for a non-QM mortgage. These loans come with more flexible credit criteria and income requirements than conventional loans, making them ideal for those who don’t fit the standard borrower box.

If your credit score or LTV was the problem, you can also consider loans through the Federal Housing Administration (FHA) and Veterans Administration (VA). Their terms are more generous, geared toward borrowers with lower credit scores or little cash for down payments.

Manual underwriting

The vast majority of conforming loans — those eligible to be bought by Fannie and Freddie — are decided via automatic underwriting. It’s fast, cheap and takes bias out of the process. But some loans still are reviewed by a human. Lenders often do manual underwriting when an application would likely be denied through an automated system, or if the borrower has some unusual circumstances but is otherwise qualified.

Certain types of mortgages, like jumbo loans and non-QM loans, are more likely to be manually underwritten. But you can request it for any mortgage, if you believe your particular situation will not be fully understood by the ‘bot. Be prepared to supply additional paperwork — financial statements reaching farther back, for example — and for a longer process. Bear in mind that, even with a manual underwriter, your loan still has to conform to specific requirements.

Bottom line

The mortgage application process can be full of surprises — with a key one being that an automated underwriting system often decides your approval or denial. The key reasons for rejection often involve credit score issues, income shortfalls, high loan-to-value ratios, property type, or recent changes in your financial situation. But the ‘bot doesn’t necessarily have to have the last word. Find out why your application was denied, and then seek remedies: explore alternatives to conventional conforming loans, or request manual underwriting (a review by a human underwriter). Any of these may provide a pathway to homeownership.

Chicago White Sox manager Pedro Grifol gives an offseason update — including what he recently told starter Dylan Cease

posted in: News | 0

Chicago White Sox players participated in an obstacle course with kids at the Boys & Girls Clubs of Chicago during a surprise visit Thursday in Bridgeport.

The Sox experienced several hurdles last season on the way to 101 losses. They’ll attempt to find the path to improvement with pitchers and catchers scheduled to report to spring training Feb. 14.

Manager Pedro Grifol isn’t thinking about the first game of the season or beyond.

“I’m thinking about the first week of spring training and we’ve got to win that first week,” Grifol said at Thursday’s event. “We’ve got to go into spring training and prepare ourselves to win baseball games. We’ll take it five to seven days at a time and we’ll continue to evaluate the week and correct the things we need to correct and go from there.

“There’s a lot of work to be done before that first game. There’s a lot of conversations between our staff and the players and we’ll be ready to play come day one.”

There have been pitching and hitting summits since the final out of the woeful 2023 season.

“Once that last game was over, the calendar changed for us,” Grifol said. “There’s been really good communication. (General manager) Chris (Getz) installed the pillars he wants the organization to abide by. I’ll have my style of play I want to see on the field and the players will be a part of the process.

“There is a lot of things that are different (this spring compared to last). The energy in spring training I thought last year was OK, but it’s hard to evaluate it because we had so many guys who weren’t there (with the World Baseball Classic taking place). But that’s something we’re going to focus on, the details are something we’re going to focus on.”

Grifol knows it has to be more than just talk.

“When I put myself in the eyes of the fans, we’ve got to prove it on the field,” he said. “I can stand here today and say, ‘We’re going to do this or do that.’ That’s not what this is about. This is about us preparing ourselves to play and prove to our fans — they had a difficult year last year — that we’re going to come out and play a different style of baseball.”

Grifol said he’s most excited about getting to spring training “because the energy we have, that our players are showing, the energy that our front office and coaching staff is showing. We have five new coaches on our staff. And plus what we did last year. We’re motivated, we’re excited to come back and prove to this league that we’re capable of doing some good things. I just feel it, there is a good vibe.”

Grifol likes the moves the team has made this offseason and anticipates a lot of competition at camp.

“Last year we went into spring training probably six or seven starters deep, this year you’re probably looking at 15-16 starters,” he said. “Some of these guys are young, some ended the year in Double A, some in Triple A. Just to look at our depth compared to where we were at this time last year is really encouraging for us.”

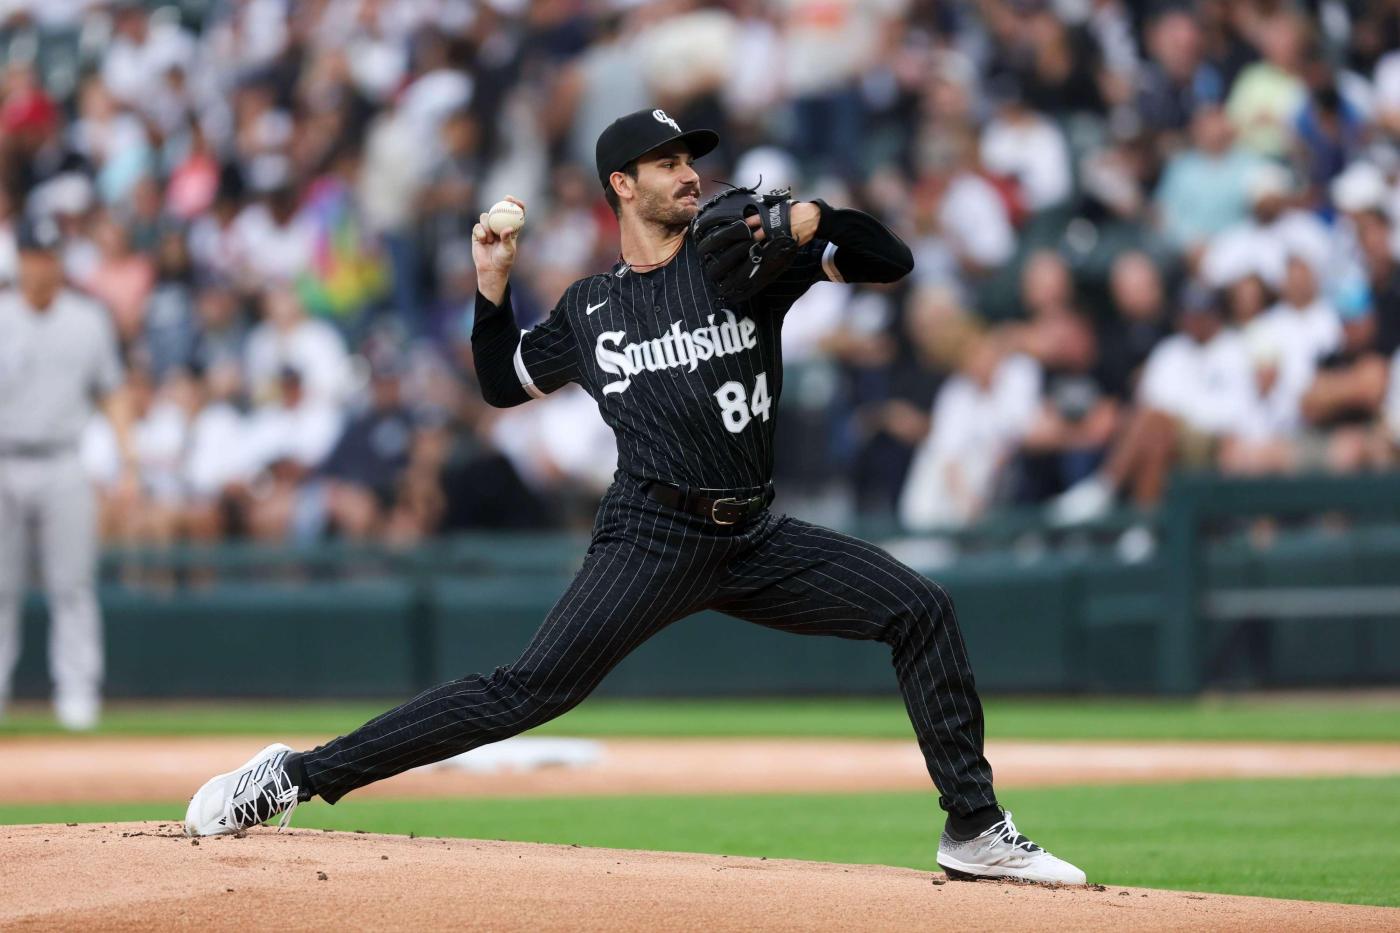
One of those experienced starters could be Dylan Cease, who has been mentioned in trade speculation throughout the offseason. Grifol said Cease has been “unfazed” by the chatter.

“I talked to him yesterday, it was a great conversation and we talked about him (pitching) opening day,” Grifol said. “And he’s preparing himself for that and he feels great. He’s throwing pens, he doesn’t have any soreness, he’s excited about this club. He’s excited about the guys we’ve acquired, excited about our catching. Brian Bannister is part of the organization (as senior adviser to pitching), he’s excited to get to work with him and (pitching coach) Ethan (Katz).

“He’s unfazed by all these trade talks and all this stuff. If it happens, he understands the business. But like I told him and he told me, right now he’s our opening-day starter and get ready to do that.”

()

Watch: St. Paul Mayor Melvin Carter delivers ‘State of the City’ address

posted in: News | 0

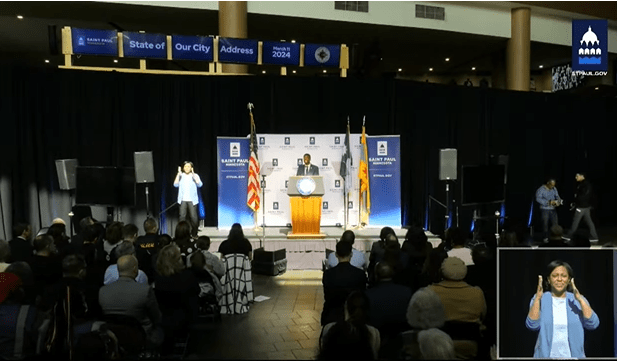
The 2024 State of Our City Address began at noon on Monday at the Xcel Energy Center, Gate 1, in downtown St. Paul.

The event is free and open to the public.

People can listen to St. Paul Mayor Melvin Carter give the address in person, watch the city’s Facebook or YouTube livestream or tune into the City’s cable channels, Comcast 18 and 859.

Related Articles

Local News |


Shooting in St. Paul apartment building leads to SWAT team response

Local News |


Melvin Carter to deliver State of the City address: Housing, hiring and plowing on the agenda

Local News |


Twin Cities janitors reach tentative deal after months of bargaining

Local News |


Concert review: St. Paul Chamber Orchestra celebrates Black cultural connections, shifts gears to Antonín Dvořák

Local News |


As hockey fans converge on the X in St. Paul, nearby restaurants see one of their busiest weekends of the year