Biden campaign slams ‘extreme’ and ‘racist’ Trump immigration plans

posted in: Politics | 0

The Biden campaign on Saturday lambasted Donald Trump’s reported plans for an extreme and rapid expansion of his first-term clampdown on immigration if he takes back the White House.

If he wins the 2024 election, Trump intends to reimplement many of his first-term policies, including the so-called Muslim ban and the use of Title 42 to turn away asylum seekers. He also wants to deport migrants by the millions per year, detaining them in large camps while they await expulsion, according to a new report from the New York Times.

The former president further wants to end birthright citizenship for children born to undocumented immigrants, among other hardline policies.

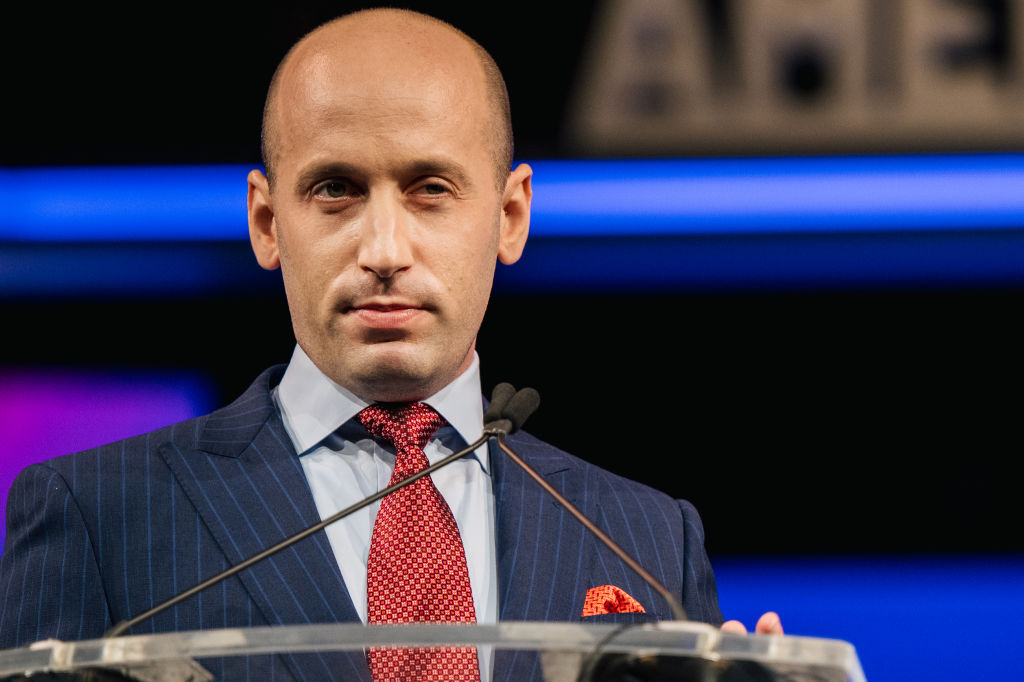
“Mass detention camps, attempts to deny children born here citizenship, uprooting families with mass deportations — this is the horrifying reality that awaits the American people if Donald Trump is allowed anywhere near the Oval Office again,” Biden campaign spokesperson Ammar Moussa said in a statement. “These extreme, racist, cruel policies dreamed up by him and his henchman Stephen Miller are meant to stoke fear and divide us, betting a scared and divided nation is how he wins this election.”

Trump has repeatedly hinted at these plans at political rallies, where he typically talks at length about the southern border. Stephen Miller, a senior aide who crafted many of Trump’s first-term policies, is once again heavily involved in the planning, according to the Times. Trump’s campaign didn’t immediately respond to a request for comment.

Immigration will once again be a political lightning rod in 2024: the Biden administration has faced similar struggles as the Trump administration to contain surging migration levels, and the Republican field has seized on the border as a base-rallying issue, proposing bombing Mexico to stop cartels and using deadly force against migrants suspected of drug trafficking.

Congress has made little progress in rebuilding an outdated system unable to manage the crisis, and negotiations on the Hill to pass Biden’s national security supplemental package have added another challenging layer as Republicans hang money for Ukraine and Israel on border policy changes.

Biden is facing bubbling political pressure within his own party, as immigration groups and progressives urge the president to not concede any long-lasting policy changes amid hasty congressional negotiations.

Immigration groups often point to Biden’s rhetoric in 2020, when he talked about restoring the asylum system decimated under the Trump administration. On his first day in the White House, Biden sent a bill to overhaul the immigration system, but it never moved in Congress.

Unable to deliver the major reform he once promised, Biden has spent his presidency combatting criticism from not only Republicans, but from Democrats who have criticized his reimplementation of Trump-era policies, such as the so-called transit ban.

While Biden’s denouncement of Trump administration policies was central to his 2020 message, it’s not yet clear how often the president will talk about immigration this go-around. But it is clear that his campaign will continue to seize on opportunities to contrast the president with his leading GOP challenger.

“The American people chose unity over division and hope over fear in 2020 when they elected Joe Biden and Kamala Harris and sent Donald Trump packing, and they’ll do it again next year,” Moussa said.
Biden commemorates Veterans Day as conflicts escalate abroad

posted in: Politics | 0

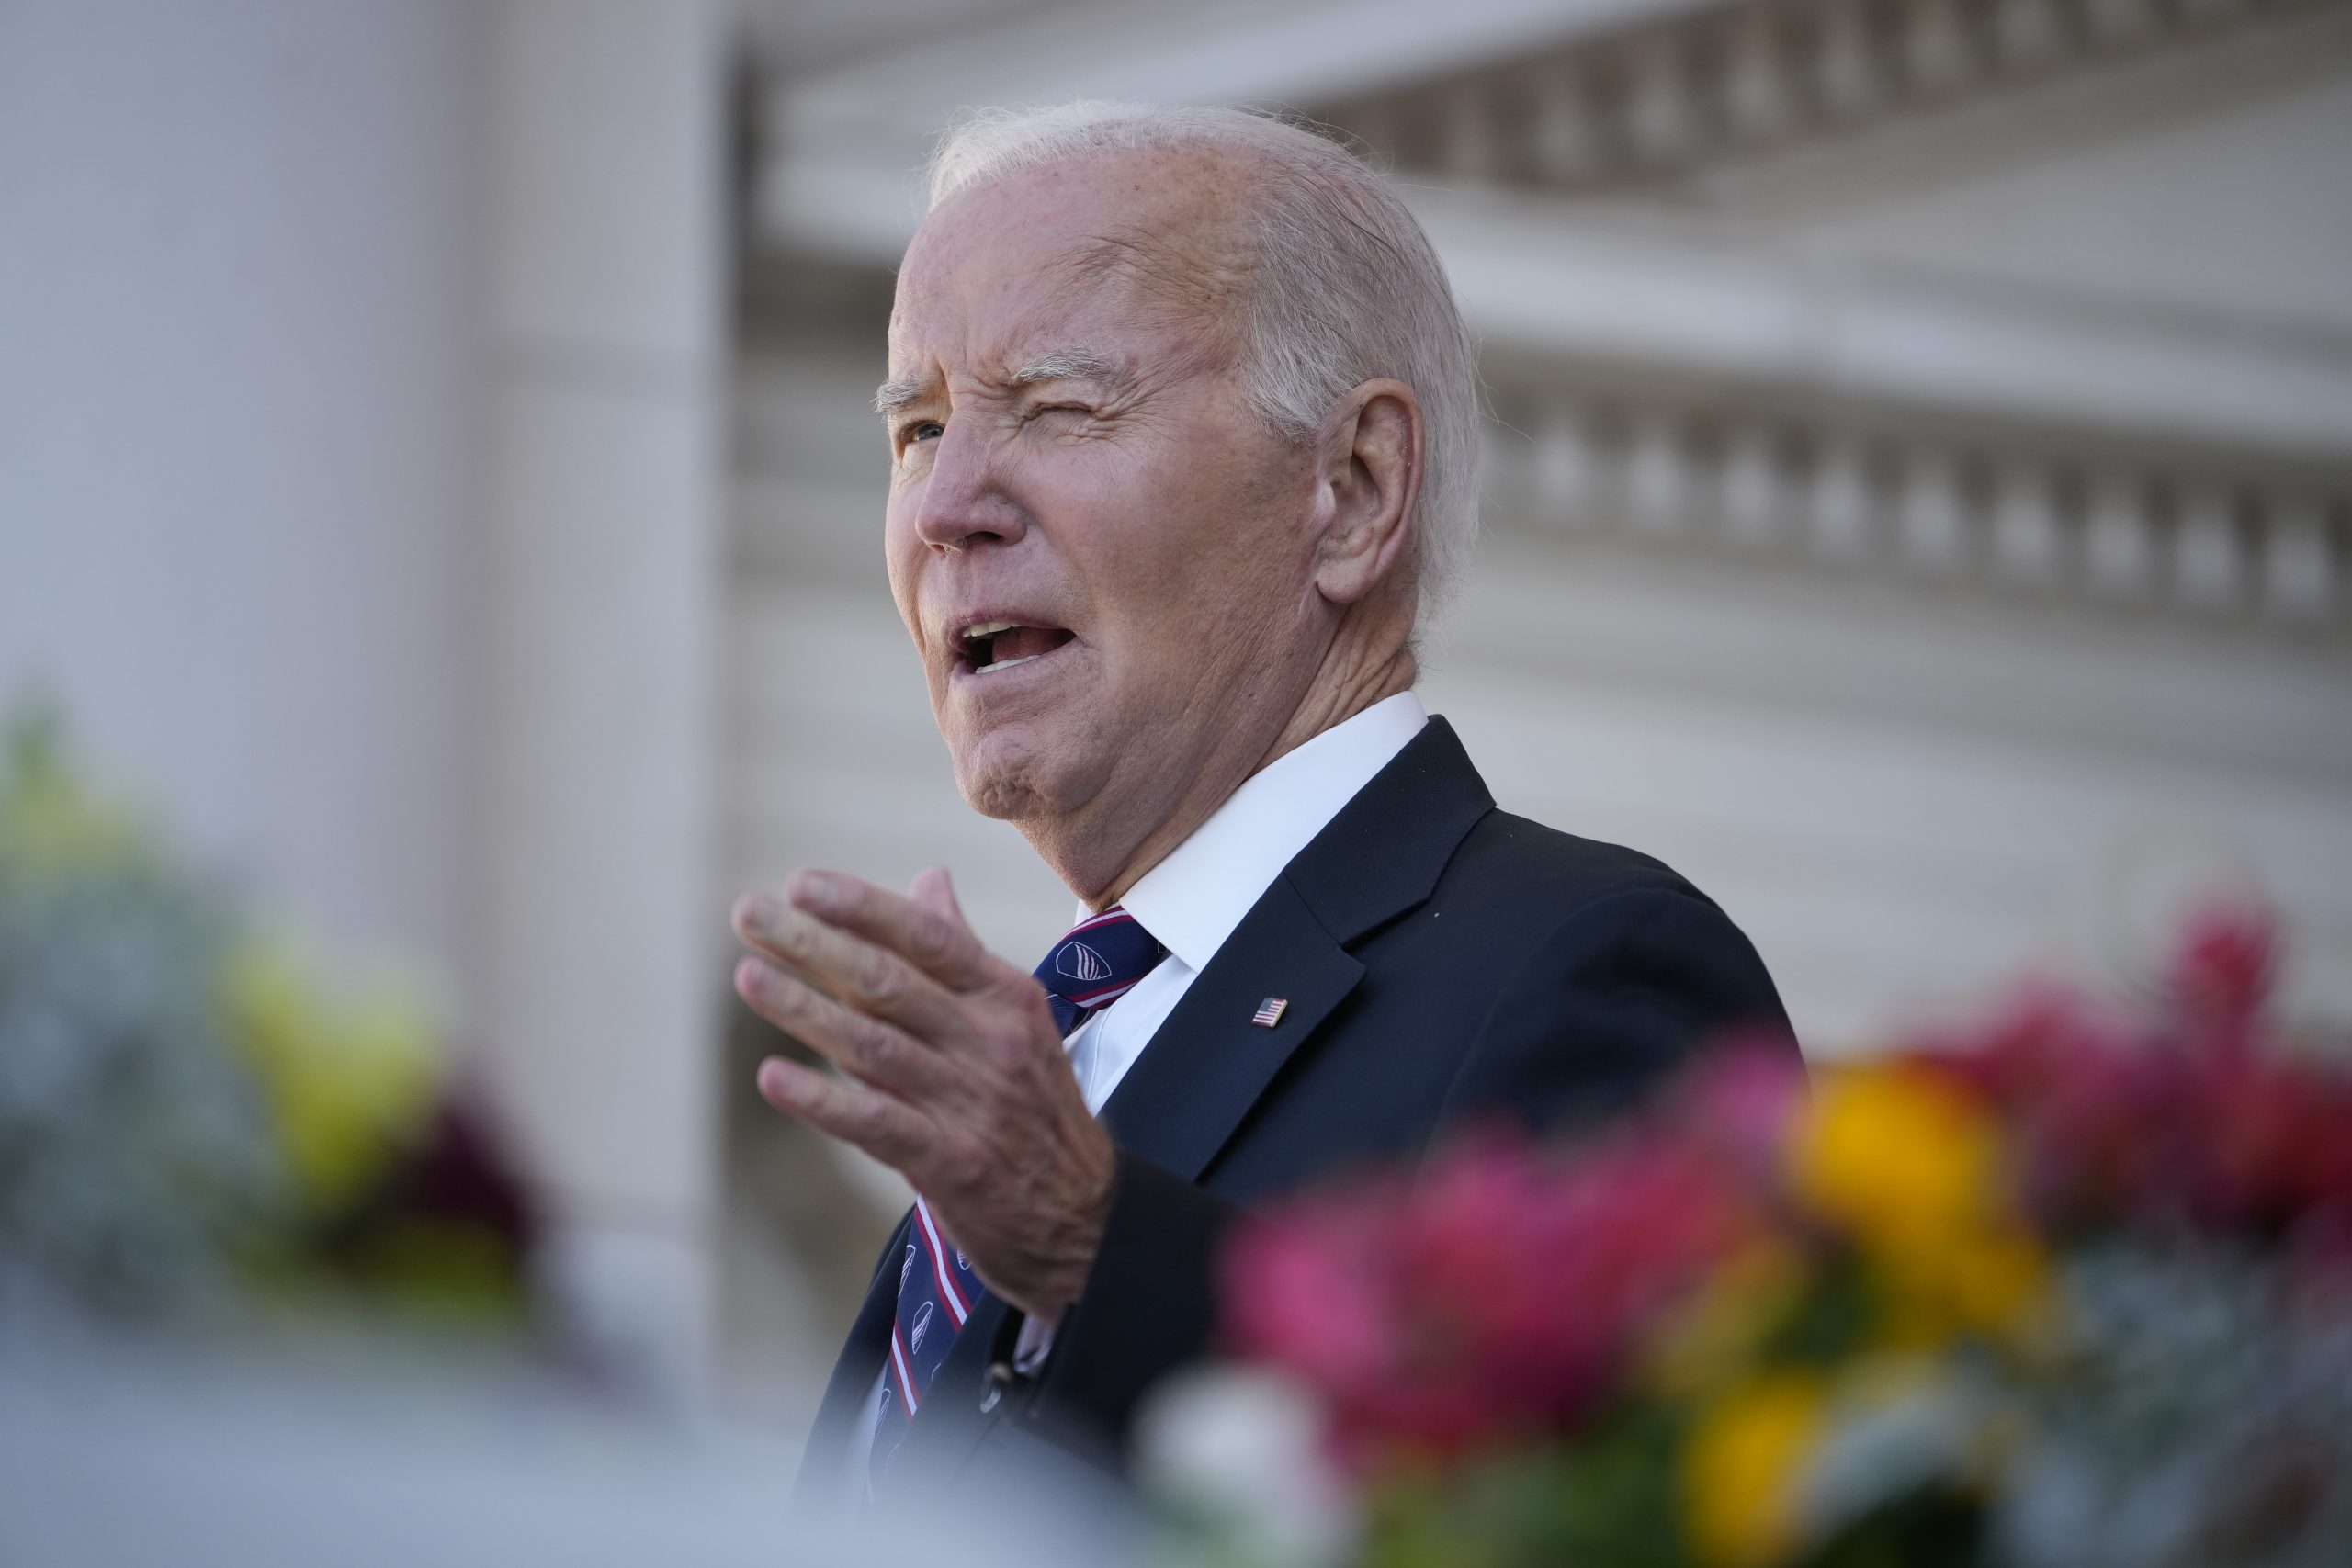
With the U.S. facing increasing involvement in two wars, President Joe Biden addressed current and former servicemembers at Veterans Day ceremonies Saturday at Arlington National Cemetery.

Although Biden did not explicitly mention the ongoing conflicts in Ukraine and Gaza, his speech focused on American forces rising to the occasion to defeat darkness and evil.

“Whenever and wherever the forces of darkness have sought to extinguish the light of liberty, American veterans have been holding the lantern as high as they can for all of us,” he said, speaking at the Memorial Amphitheater after placing a wreath at the Tomb of the Unknown Soldier.

Biden was joined by Vice President Kamala Harris, Secretary of Veterans’ Affairs Denis McDonough and top military officials.

“Our veterans are the steel spine of this nation, and their families, like so many of you, are the courageous heart,” Biden said.

Although there are no American boots on the ground fighting in the conflicts in Ukraine or Gaza, the U.S. is a major provider of military aid and security assistance to Ukraine in its war with Russia, and to Israel in its war with Hamas.

Biden’s speech highlighted the PACT Act, which was signed into law last year. The legislation aimed to expand healthcare access for veterans exposed to toxic chemicals and their families.

“Too many of our nation’s warriors have served, only to return home to suffer from permanent effects of this poisonous smoke,” Biden said, adding that all veterans who had been exposed to toxins while serving in any conflict included in the PACT Act would become eligible to enroll in VA healthcare starting in March 2024.

The Biden-Harris campaign also aired a TV ad focused on the legislation, timed to Veterans Day.

Biden’s son, Beau Biden, died of brain cancer after serving in Iraq, where he was exposed to burn pits.

“On this day, I can still see my son, Attorney General of Delaware, standing ramrod straight as I pinned his bars on him the day he joined the Army and National Guard in Delaware. I can still feel the overwhelming pride of Major Beau Biden receiving the Bronze Star, the Legion of Merit and the Delaware Conspicuous Service Cross,” he said. “We miss him.”

“Today I see that light of liberty. We live by it, just like our forebears. So all of us together, to ask ourselves, what can we do, what must we do to keep that light burning?” Biden said, concluding his remarks.

With offseason underway, here are three areas of interest for the Twins

posted in: News | 0

The offseason moves have begun.

The Twins picked up the club options on second baseman Jorge Polanco ($10.5 million) and Max Kepler last week. They also extended a qualifying offer to starting pitcher Sonny Gray. Gray, who is widely expected to decline the offer and test free agency, has until Nov. 14 to make a decision.

As the offseason begins, it has become clear that the Twins’ payroll will not be as high as it was in 2023, in part because of the end of their television contract, when it was at their all-time high around $155 million. That could force the Twins to be more creative when trying to address roster needs this season. Here’s a look at three of their most important areas to address this winter:

Starting pitching

Kenta Maeda is a free agent. And in a matter of days, if Gray declines the qualifying offer, he will be a free agent as well — and one who will likely command a multi-year deal richer than what Twins would be willing to offer him.

The Twins have Pablo López, Joe Ryan, Bailey Ober and Chris Paddack in place, with Louie Varland as an option to start, as well.  But they’ll need to add some depth in the form of at least one starting pitcher —and finding one of Gray’s caliber or close to it won’t come cheap.

If the Twins aren’t going to be major players in free agency, as it seems, that would mean they’ll have to part with either major league or prospect talent to fill the spot via trade. The Twins have often gone this route instead of free agency to restock their rotation — Gray, Maeda, López, Ryan, Paddack and Tyler Mahle are all recent starters whom the Twins have acquired via trade.

Center field

The Twins have one of the best defensive center fielders in the game on their roster — they just don’t have any sense for how many games they might be able to rely upon him at the position.

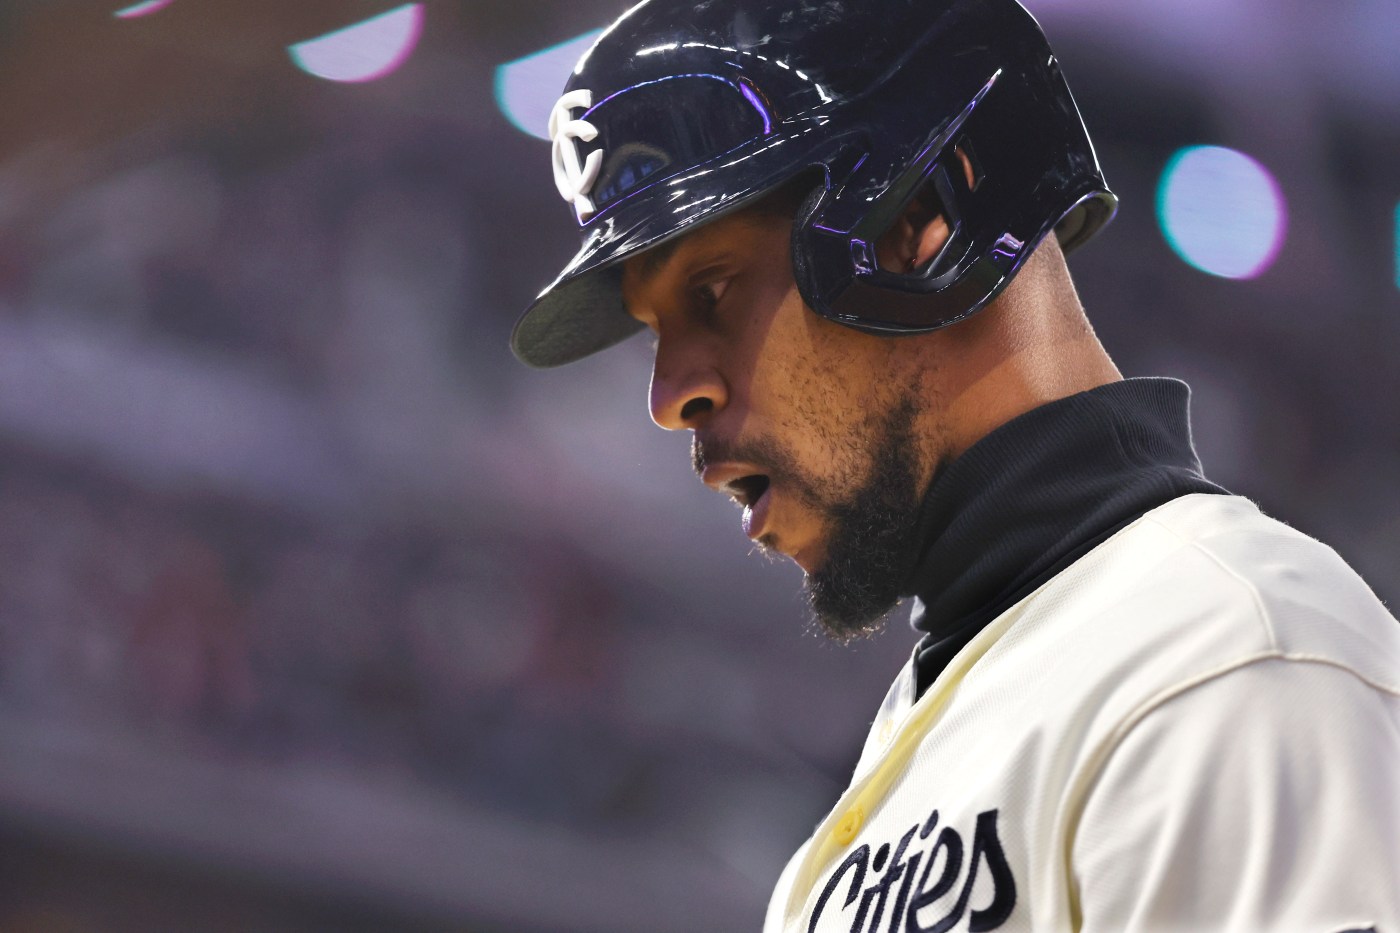
Byron Buxton did not play a single major-league game in the outfield last season, meaning the Twins must make alternate plans for the position as an insurance policy. The 29-year-old underwent a second knee surgery this offseason in hopes that he could get back into the outfield next season, but at this point, it’s hard to envision him having a starter-type workload.

Michael A. Taylor was acquired last year to be Buxton’s backup but instead turned into the starter in center with Buxton entrenched at designated hitter. Taylor is a free agent and the Twins could try to bring him back or look at other options. Harrison Bader and Kevin Kiermaier are among the other center fielders on the free-agent market who could be within the Twins’ price range if they choose to go that route to address the position.

First base

The Twins’ other needs pale in comparison to the first two, which are of much bigger concern. With Emilio Pagán ticketed for free agency, they could be in the market for some relief pitching help, though this front office has never invested heavily in relief arms.

They’ll also need an answer at first base, which will require assessing Alex Kirilloff’s readiness after an offseason shoulder surgery — one which was less invasive than they initially thought it might be.

The hope is that Kirilloff can handle much of that workload, but the former first-round draft pick’s first three seasons in the majors have all ended in surgery — two on his wrist, one on his shoulder — and the 26-year-old has never played 90 games in a season.

Last year, the right-handed Donovan Solano took a good amount of the at-bats at first base, but Solano is now a free agent. Among the internal options, perhaps Jose Miranda could play some first base, though the Twins don’t have great clarity on what to expect from him after his own shoulder injury led to a lost season for the 25-year-old.

That could lead the Twins to potentially look externally for another right-handed option who can play some first base.

Related Articles

Minnesota Twins |


Sonny Gray named Cy Young Award finalist; Twins extend veteran a qualifying offer

Minnesota Twins |


Twins add two to 40-man roster; more prospect additions coming

Minnesota Twins |


Twins pick up club options on Max Kepler, Jorge Polanco

Minnesota Twins |


Longtime Twins broadcaster Dick Bremer stepping away from booth, into special assistant role

Minnesota Twins |


Twins position breakdown: designated hitter

Your Money: A year-end tax-planning checklist

posted in: Society | 0

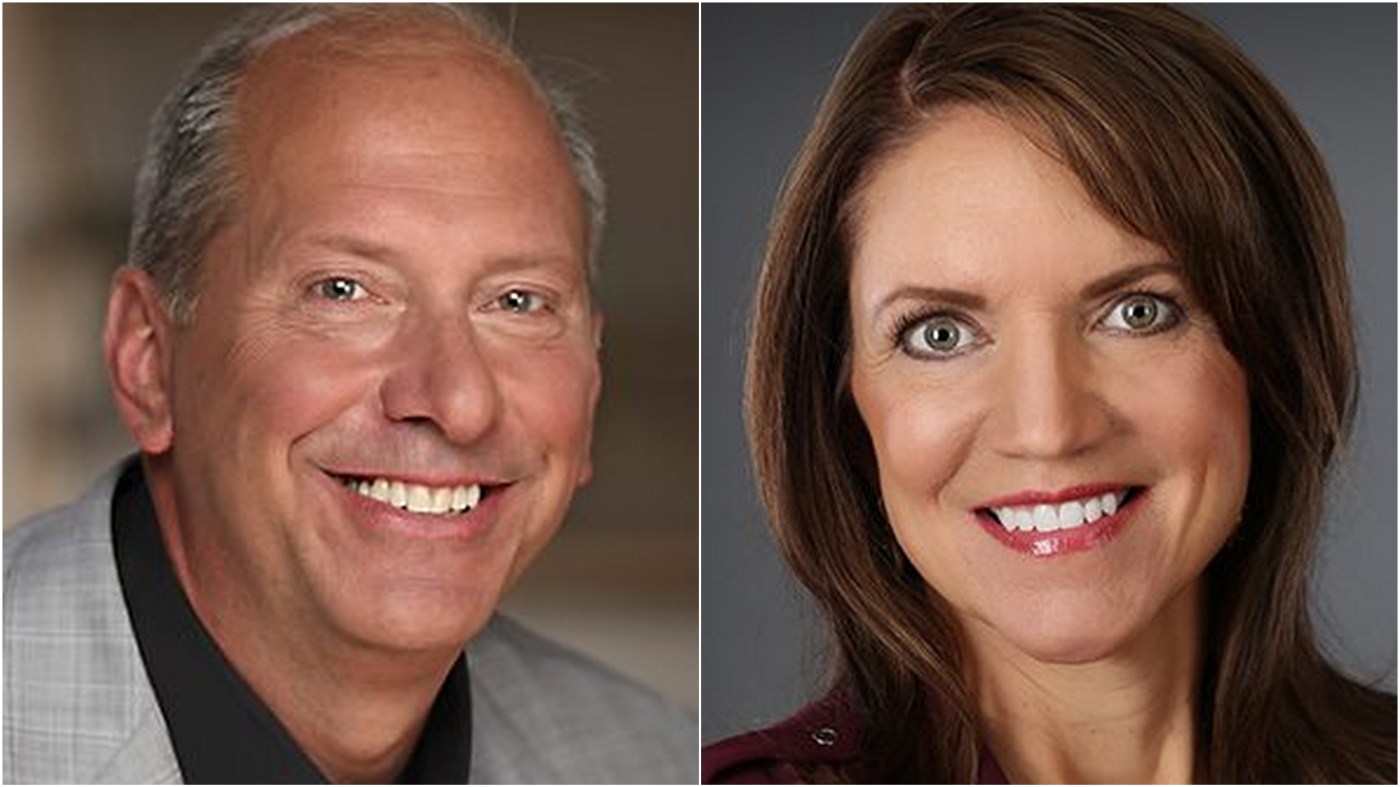
Bruce Helmer and Peg Webb

For many investors, taxes represent their biggest investment expense, consuming upwards of a third of their earnings, depending on how the assets are held. Today’s article is focused on the things you can do between now and the end of the year to lessen the impact of taxes on your 2023 tax returns.

Lower your tax bill with tax-loss harvesting

Many investors take tax losses at the end of every year for a big tax benefit, also looking at it as a kind of consolation prize for making a bad investment pick. Tax-loss harvesting is a strategy that allows you to offset some of your realized capital gains with realized losses.

To know if tax-loss harvesting is viable for you, you need to know your tax rate. For the 2023 tax year, it is a top rate of 20% for long-term cap gains — depending on your income. The rate that applies to your income could be 0%, 15% or 20% (the IRS says most people pay no more than 15%). The ordinary income tax rate that applies to short-term gains and qualified taxable distributions maxes out at 37%, but, again, the range is income dependent, beginning at 10% and rising in increments to 12%, 22%, 24%, 32%, 35% and 37%.

Some mutual funds have been throwing off sizable distributions in both short- and long-term gains; these need to be factored into your consideration of whether to use tax-loss harvesting. Keep in mind that capital losses may also be applied to current or future cap gains and income, which the Tax Code limits to $3,000 per year plus carryforwards. This means if you had significant investment losses in 2022 or previous years, you may have tax-loss carryforwards that can be applied to your 2023 tax bill.

As always, we recommend checking with your financial adviser or accountant to see if tax-loss harvesting is appropriate for your situation and tax bracket, for several reasons. For example, end-of-year rebalancing of your portfolio may be appropriate if market performance has put your target allocation out of whack. While selling a low-performing asset could help restore your desired allocation, you need to pay attention to cost basis. It generally doesn’t make sense to realize a tax loss if the sale doesn’t fit your portfolio or investment strategy or if you reasonably expect the investment to recover value in the next year or two. Plus, you need to consider the wash-sale rule that applies to the sale and repurchase of “substantially identical” assets for 30 days before and after the sale.

Tax-gain harvesting may help you avoid the related risk of higher capital gains tax rates by selling appreciated assets in lower-income years if you happen to be in a lower tax bracket. You’ll pay 0% in federal capital gains tax if you meet certain income thresholds ($89,250 if you’re married-filing-jointly or $44,759 if you’re a single filer). Tax-gain harvesting also can be useful for pass-through businesses with an expected operating loss in 2023 but that expect to be profitable in 2024.

Retirement planning is getting more complicated

Higher-than-normal inflation, rising interest rates and increased uncertainty about the direction of the economy are clouding the retirement landscape for many investors. We continue to counsel clients to use long-term inflation assumptions of 2% to 3%, especially when modeling your income needs over a retirement that could last two or three decades.

Rising interest rates are generally helpful for retirees on fixed incomes, but can be hazardous to stocks if rates pass certain thresholds. This is a good time to revisit your target asset allocation and make sure it still reflects your investment goals and risk tolerance.

And economic uncertainty can create “sequence of returns” risk if you are planning to retire in the near term. This occurs when you take out big withdrawals early in retirement when the market’s down. Remember, it’s generally better to minimize principal withdrawals during a market downturn early in retirement.

Against these unknowns, we urge investors to focus on what you can control if you are near or in retirement. That means maximizing contributions to tax-deferred accounts, making sure to take any required minimum distributions (RMDs) before Dec. 31, 2023, and considering a Roth IRA conversion, especially if you anticipate needing to minimize taxable income during your retirement years.

Review tax withholding in view of higher interest rates

Your interest income from savings accounts and other interest-bearing investments accounts may generate significantly higher Form 1099s this year. Don’t get caught off guard with an unexpectedly high tax bill. Increase your withholding amount if you anticipate that interest income could put you into a higher tax bracket. It could help you avoid getting stuck with a higher tax bill in April.

With interest rates higher than they’ve been in decades, you need to be aware of which interest-bearing accounts are taxable and which are tax-exempt. Treasury bills and government money market funds, for example, are exempt from state taxes. But interest paid on bank savings accounts, prime money market accounts and certificates of deposit (CDs) are not. Asset location is almost always as important as asset allocation when it comes to tax planning.

Related Articles

Business |


Your Money: New generations redefine the meaning of work

Business |


Your Money: Squeezed in the ‘club sandwich’ generation?

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Bruce Helmer and Peg Webb are financial advisers at Wealth Enhancement Group and co-hosts of “Your Money” on WCCO 830 AM on Sunday mornings. Email Bruce and Peg at yourmoney@wealthenhancement.com. Securities offered through LPL Financial, member FINRA/SIPC. Advisory services offered through Wealth Enhancement Advisory Services, LLC, a registered investment advisor. Wealth Enhancement Group and Wealth Enhancement Advisory Services are separate entities from LPL Financial.